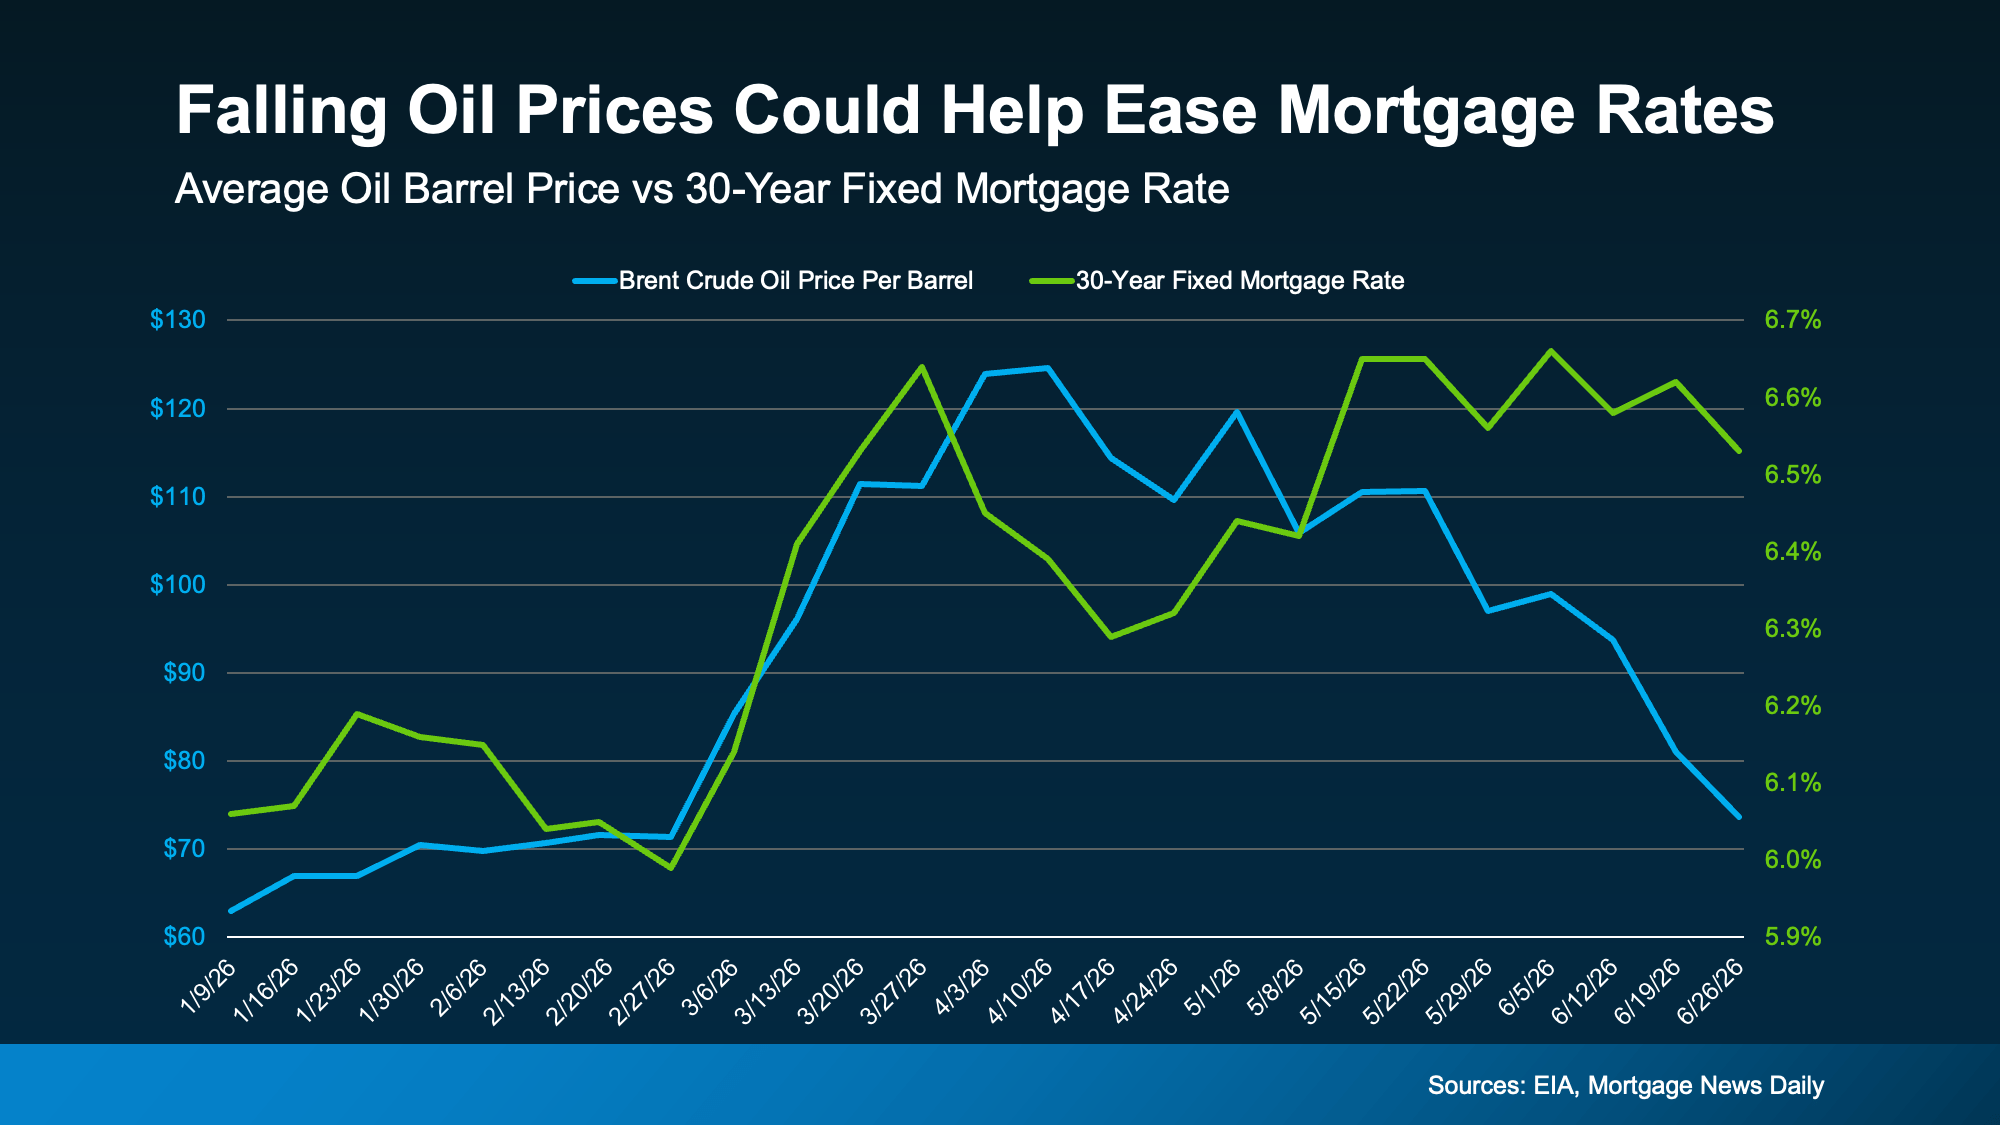Blog | Real Estate News & Market Trends

You’ll find our blog to be a wealth of information, covering everything from local market statistics and home values to community happenings. That’s because we care about the community and want to help you find your place in it. Please reach out if you have any questions at all. We’d love to talk with you!

Oct. 19, 2026

The Biggest Credit Hurdle for Renters Who Want To Buy
The Biggest Credit Hurdle for Renters Who Want To Buy


What's the biggest payment you make every month? If you’re a renter, it's probably your rent. 

But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It's pretty frustrating, especially if you'd like to buy a home someday and you’re trying to build your credit.

The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.

The Problem for Would-Be Buyers

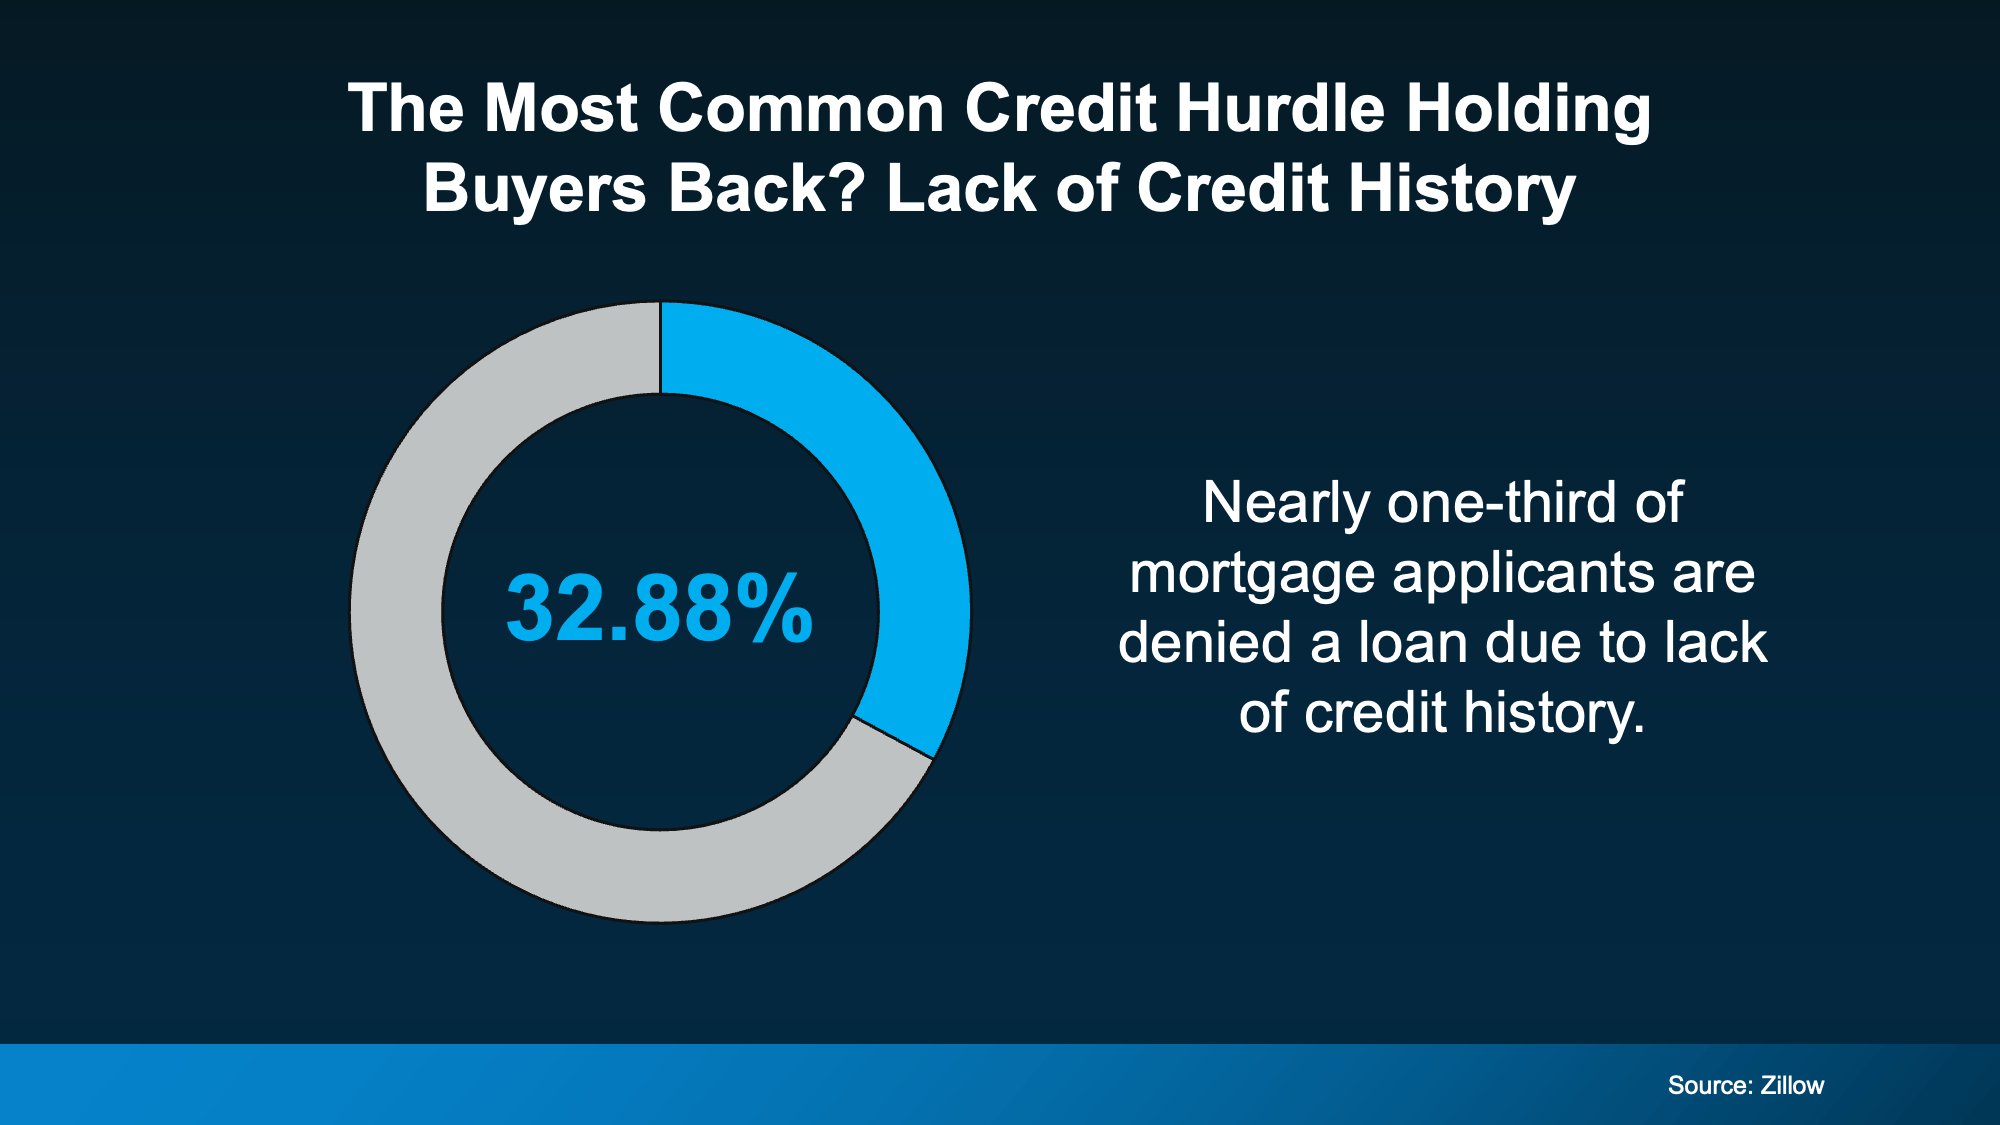
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history - not missed payments or too much debt. Just not enough credit history for a lender to say "yes."

It’s the most common hurdle would-be buyers have. As Zillow explains:

“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
a blue and grey pie chart

But there’s finally a way in now that how credit gets measured is changing.

The Good News: Credit Is Getting Broader

As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:

"Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”

Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.

VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.

A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.

Here’s the catch though, you still have to walk through it.

Counting Rental Payment History Is Not Automatic

There are more options available to build credit, but you have to be proactive. Your rent won't necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.

Here's how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:

  • Ask your landlord or property manager if your rent is being reported. If it's not, opt in. 

  • If your landlord doesn't offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.

  • Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.

  • Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don't apply for a bunch of new credit at once.

  • Don’t close any accounts - even if you have paid them off and don't use them often.

  • Diversify your profile by getting a secured credit card or becoming an authorized user on someone else's account to help you build history beyond rent.

These steps take a little time and effort, but it could be worth it if it starts building up your credit history. 

Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better. 

Even if you're not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.

Bottom Line

The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.

Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you're closer to owning a home than you think.
Posted in Buying
Oct. 5, 2026

Two Moves That Can Get You Into Your First Home Sooner

Two Moves That Can Get You Into Your First Home Sooner


For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.

But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.

How Long Buying Really Takes

First, one quick definition. "Breaking even" is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

"Buyers should think about not just when they can afford to buy, but how long they'd need to stay before owning makes more financial sense than renting."

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.

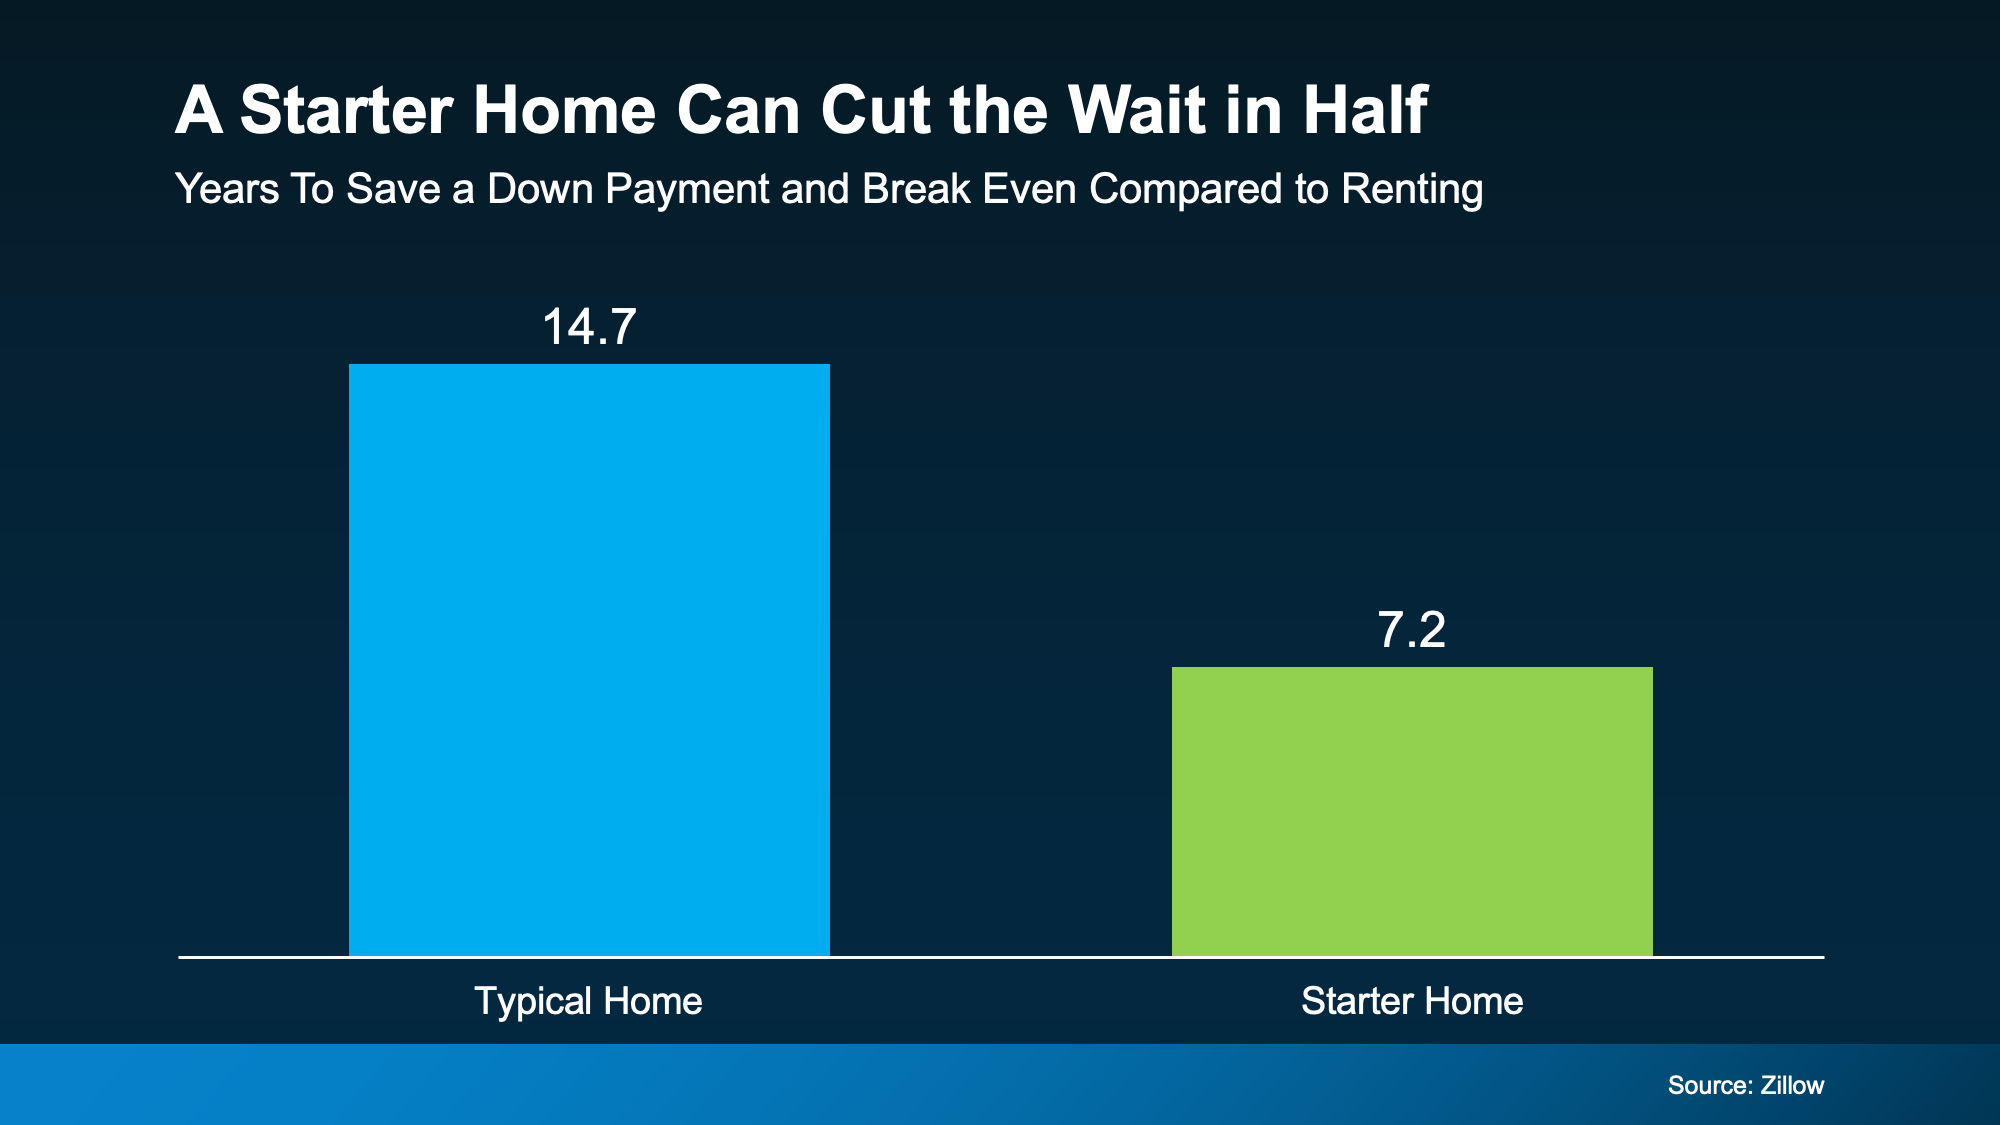
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that's just under 15 years. But that math relies on two assumptions: that you're buying a mid-priced home, and that you're putting 20% down. 

Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. 

A Starter Home Can Get You There Twice as Fast

A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. 

Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.

Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):

a graph of a number of squares

That works out to about 4.6 years to save and 2.6 years to break even. It won't erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.

You Usually Don't Need To Put 20% Down

You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. 

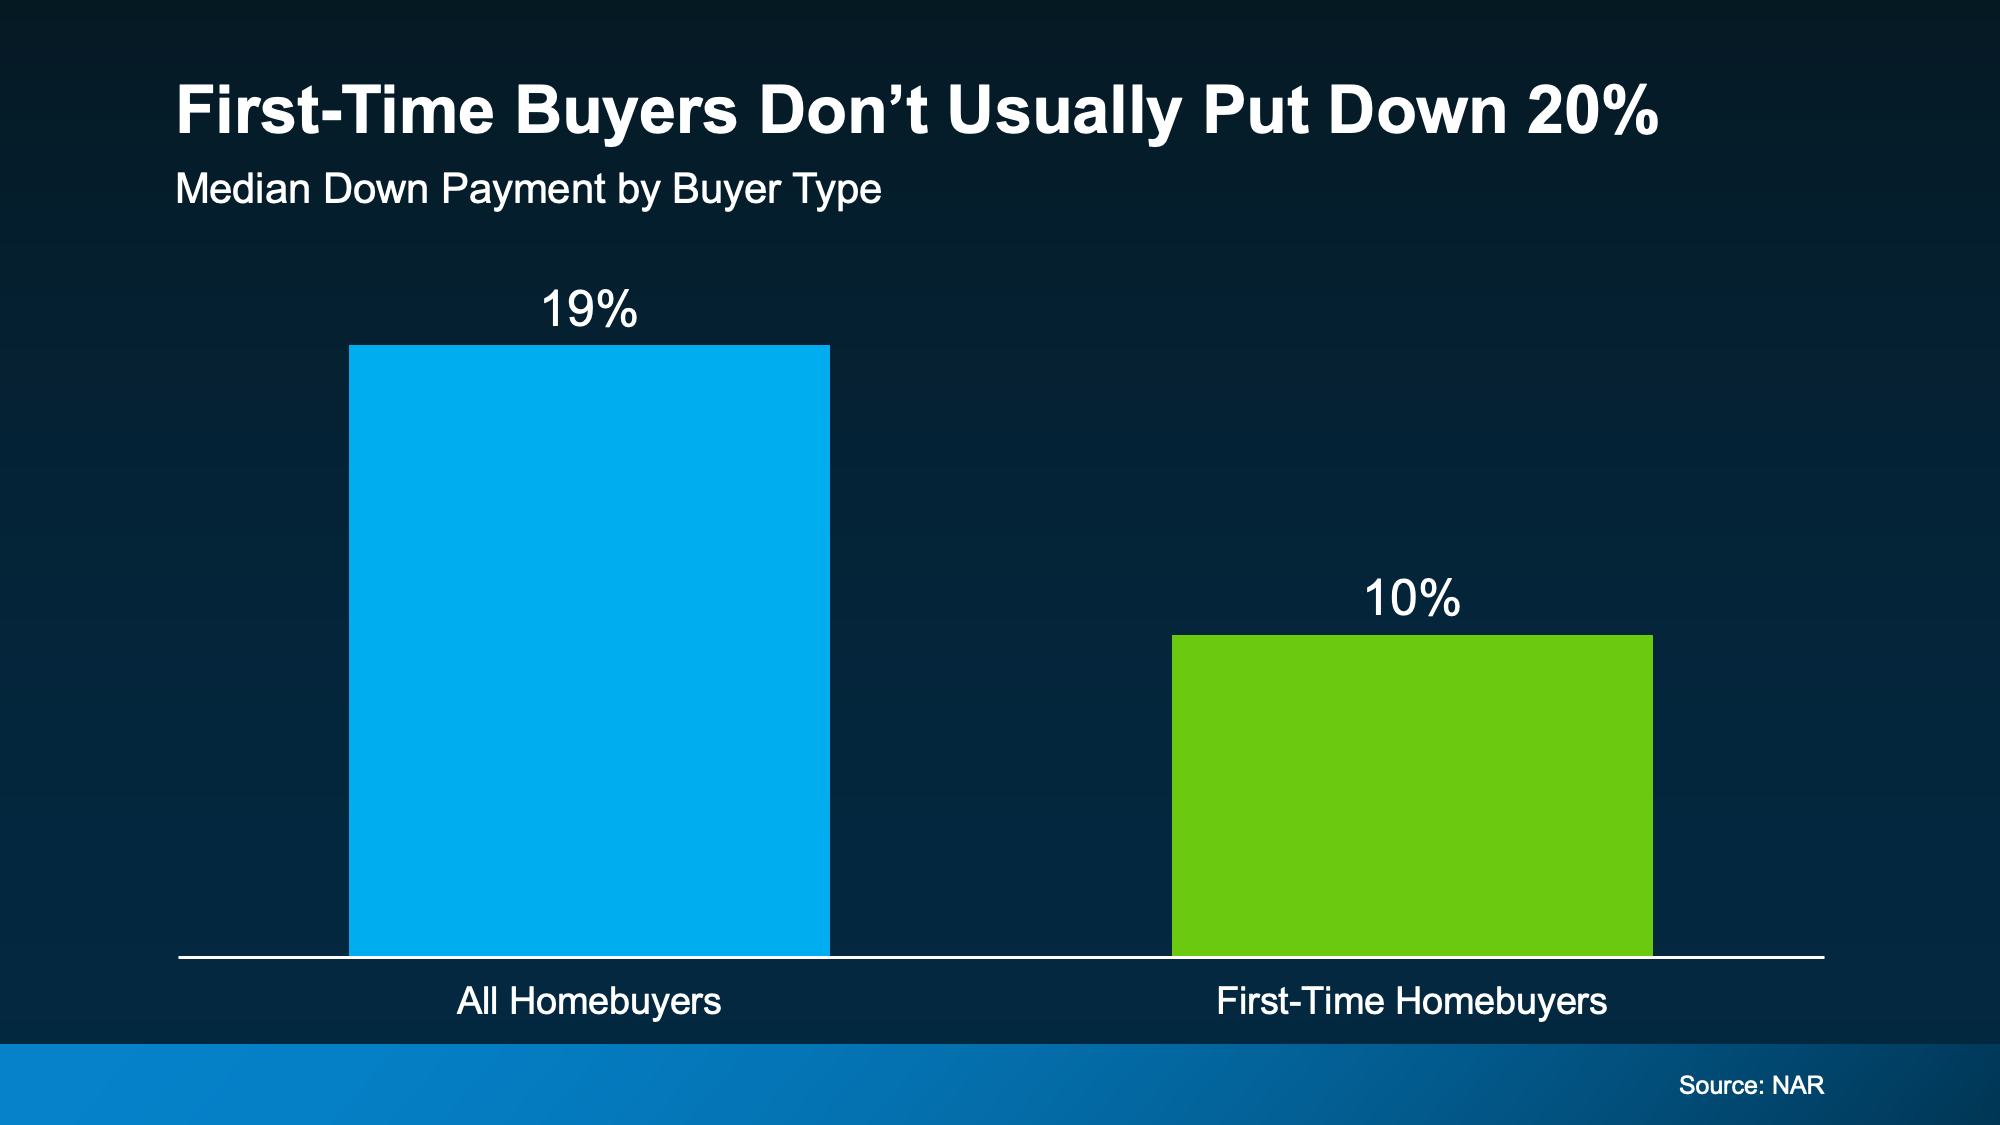
Most first-time buyers don't put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):

a graph of a sales report

And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.

There's help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

"Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase."

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.

Bottom Line

Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. 

Want to see which starter homes in our area could fit your budget? Let's connect.

Posted in Helpful Tips
Sept. 29, 2026

3 Things You Can Actually Control About Your Mortgage Rate Right Now

3 Things You Can Actually Control About Your Mortgage Rate Right Now


If you're trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and wait for them to go down.

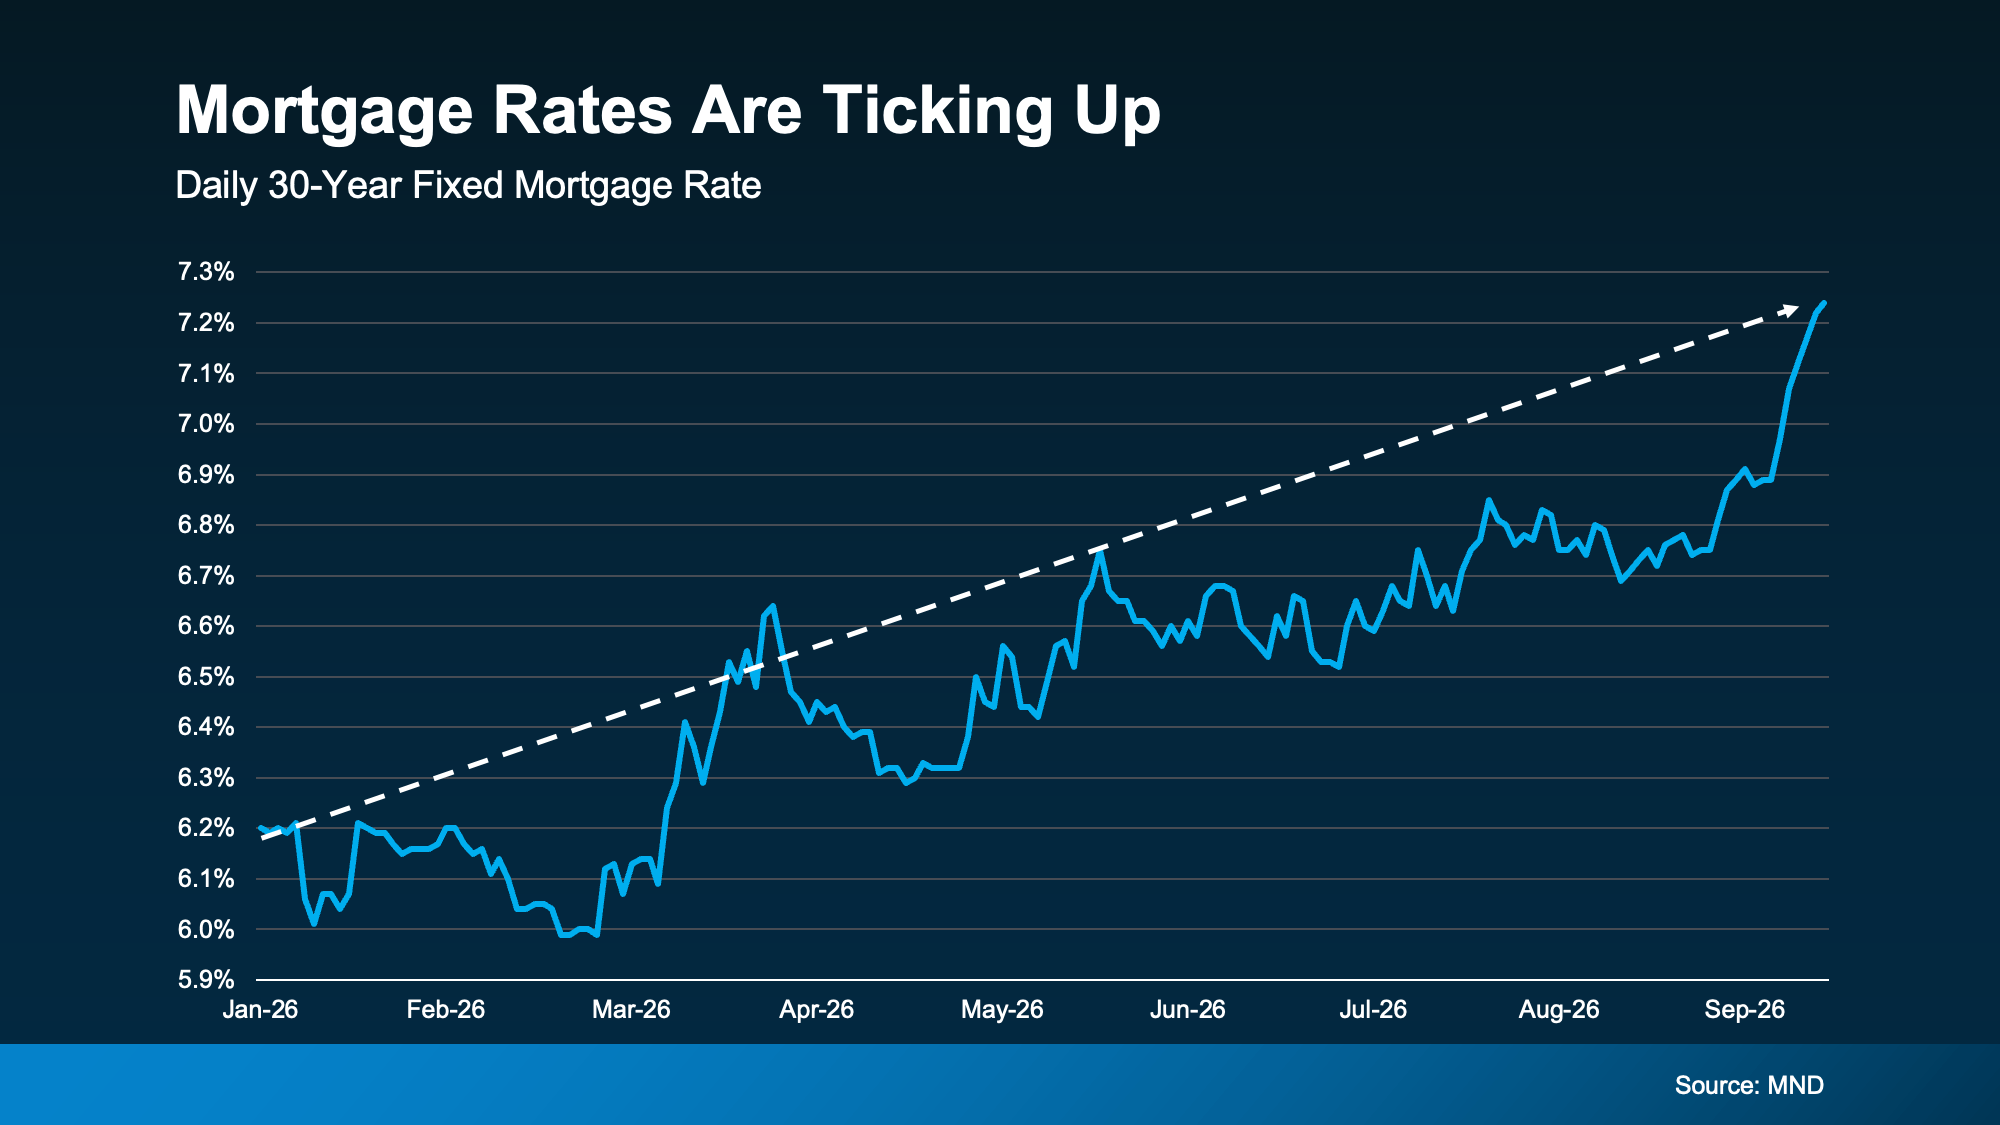
For now, though, they’re headed the other way. Mortgage News Daily data shows how rates have risen this year (see graph below):

a graph of a moving rate

And if you’re wondering why? There are actually a number of reasons. 

Mortgage rates are impacted by the situation overseas, economic data, inflation numbers, oil prices, and even decisions from the Federal Reserve (who recently decided to hike their Fed Funds Rate – which often affects mortgage rates too). As Danielle Hale, Chief Economist at Realtor.com, explains:

“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”

Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s nothing you can do. While you can't control where rates go from here, you absolutely can control several things that shape the rate you actually get. 

So where should you focus? Let's walk through it.

Work on Your Credit Score

Your credit score plays a big role in the rate you qualify for, and even a small improvement can make a real difference in your monthly payment. As Freddie Mac puts it:

"Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate."

So, make sure you do what you can to keep your credit score up. If you're not sure where your score stands right now, or how to improve it, talk to a trusted loan officer.

Explore Your Loan Options

The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each come with their own requirements and rates, and your term (15, 20, or 30 years) changes both your payment and the total interest you'll pay. The structure matters, too. A fixed-rate loan holds the same rate over time, while an adjustable-rate loan usually starts lower and can move later on. Bankrate explains it this way:

". . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk."

It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision. You may even want to talk to multiple lenders to see how the options vary. 

Consider a Newly Built Home

Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down mortgage rates, which lowers your monthly payment. It’s just one way they’re trying to attract buyers and get their homes sold.

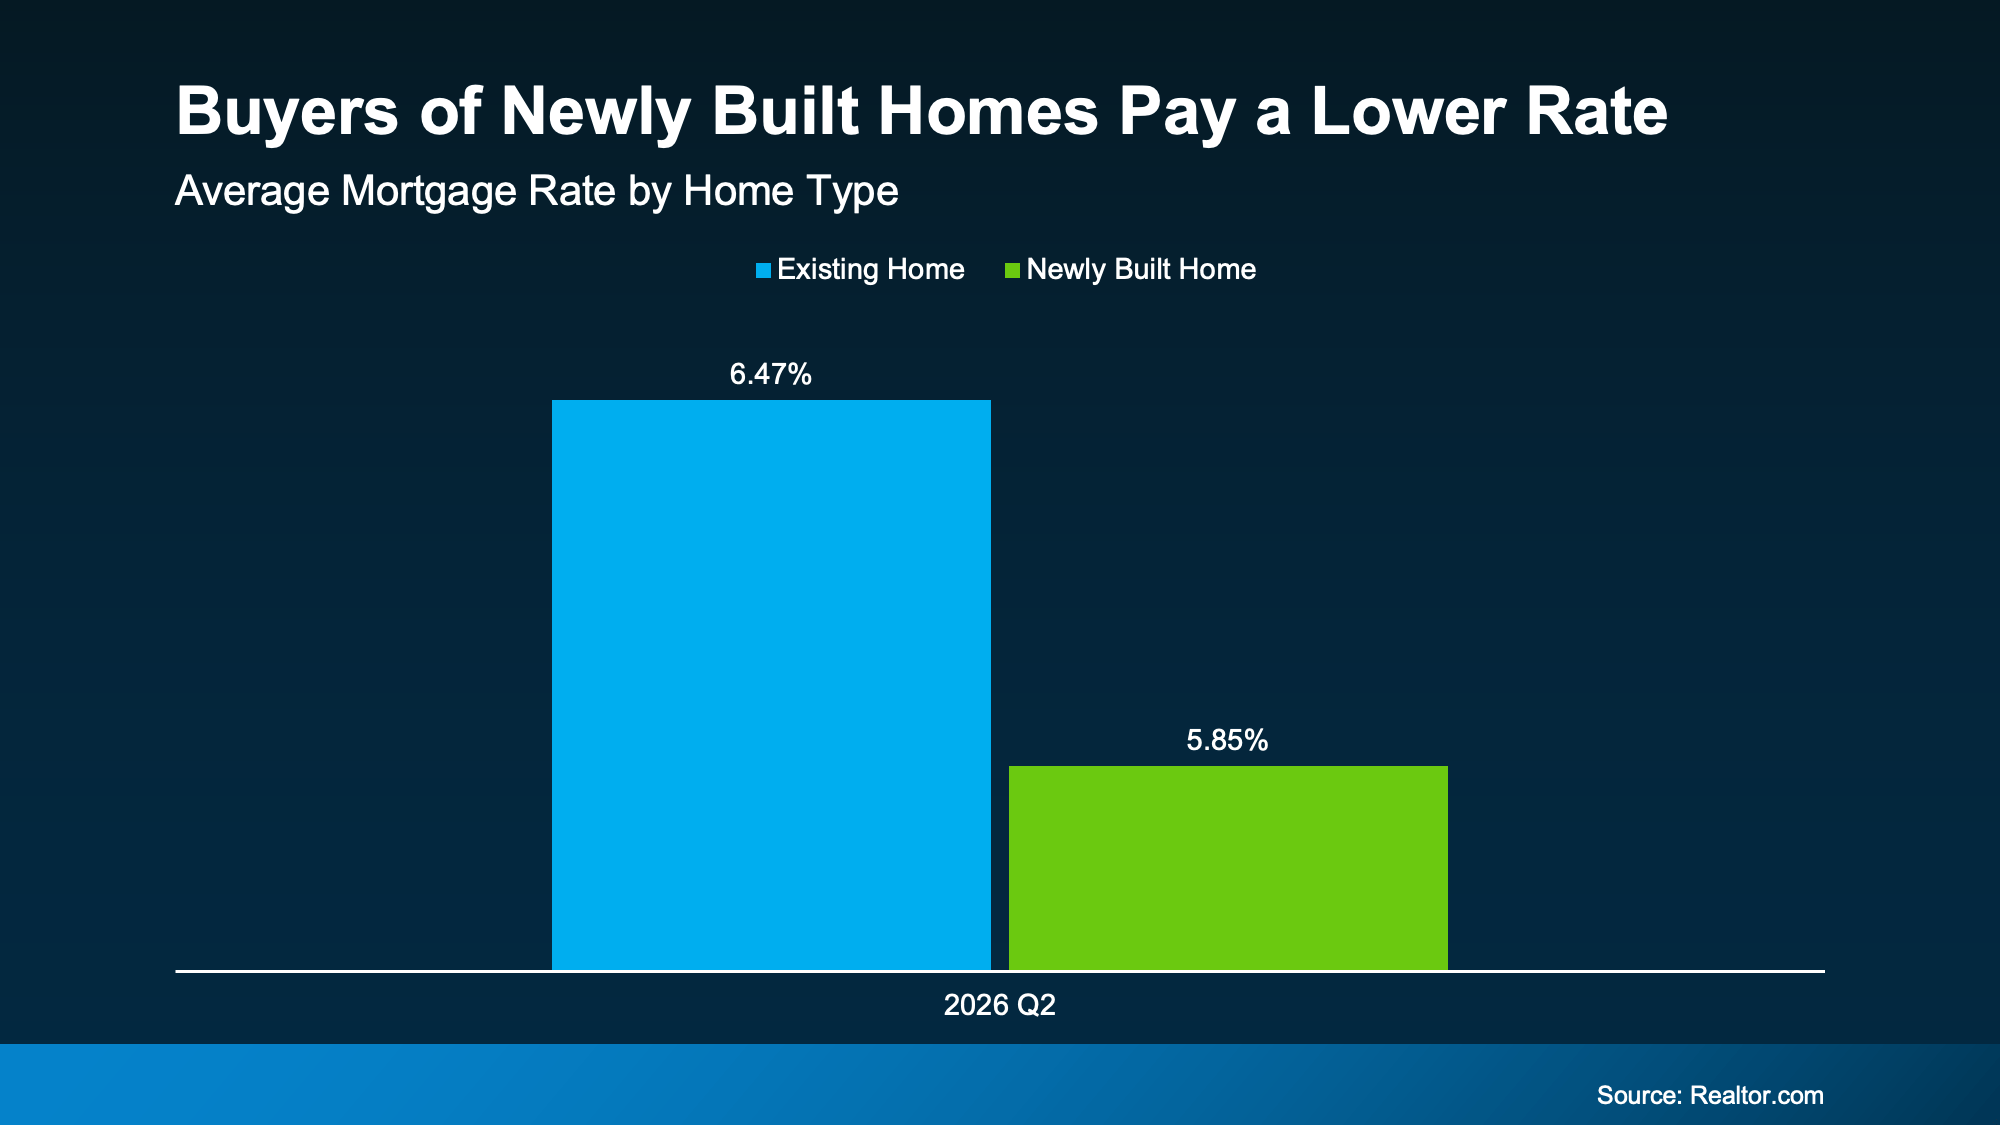
According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):

a graph of a graph showing a number of houses

If a lower rate is your goal, it may be worth asking your agent to show you some new build communities that are offering this type of incentive locally.

Bottom Line

You can't control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for. And when you’re ready to make a move that fits your budget, let’s connect.

Posted in Helpful Tips
Aug. 31, 2026

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.


Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you've caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

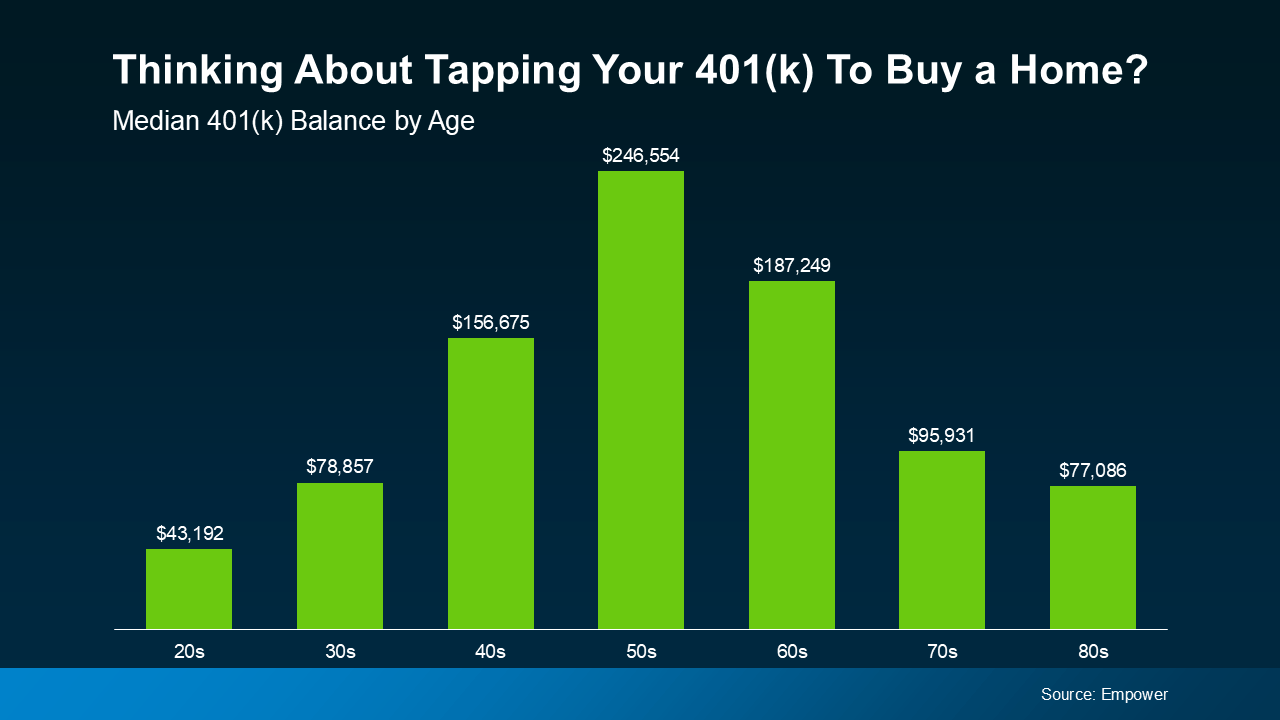
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):

a graph of green barsAnd when you've got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That's why it's a good idea to explore other options for your down payment first. As Redfin says: 

"If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth."

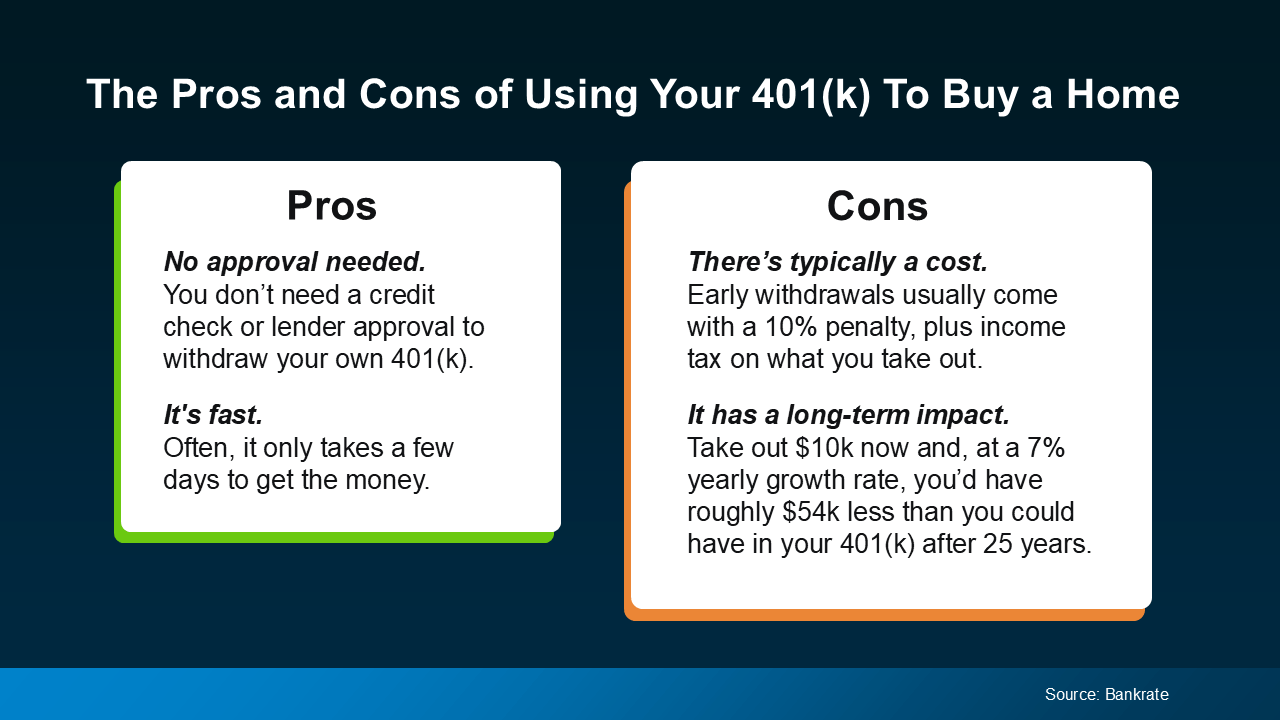
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):

a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home's price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

"Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset."

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you're considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 


Posted in Helpful Tips
Aug. 24, 2026

Most Home Sales Close – Here’s How To Keep Yours on Track

Most Home Sales Close – Here’s How To Keep Yours on Track


Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

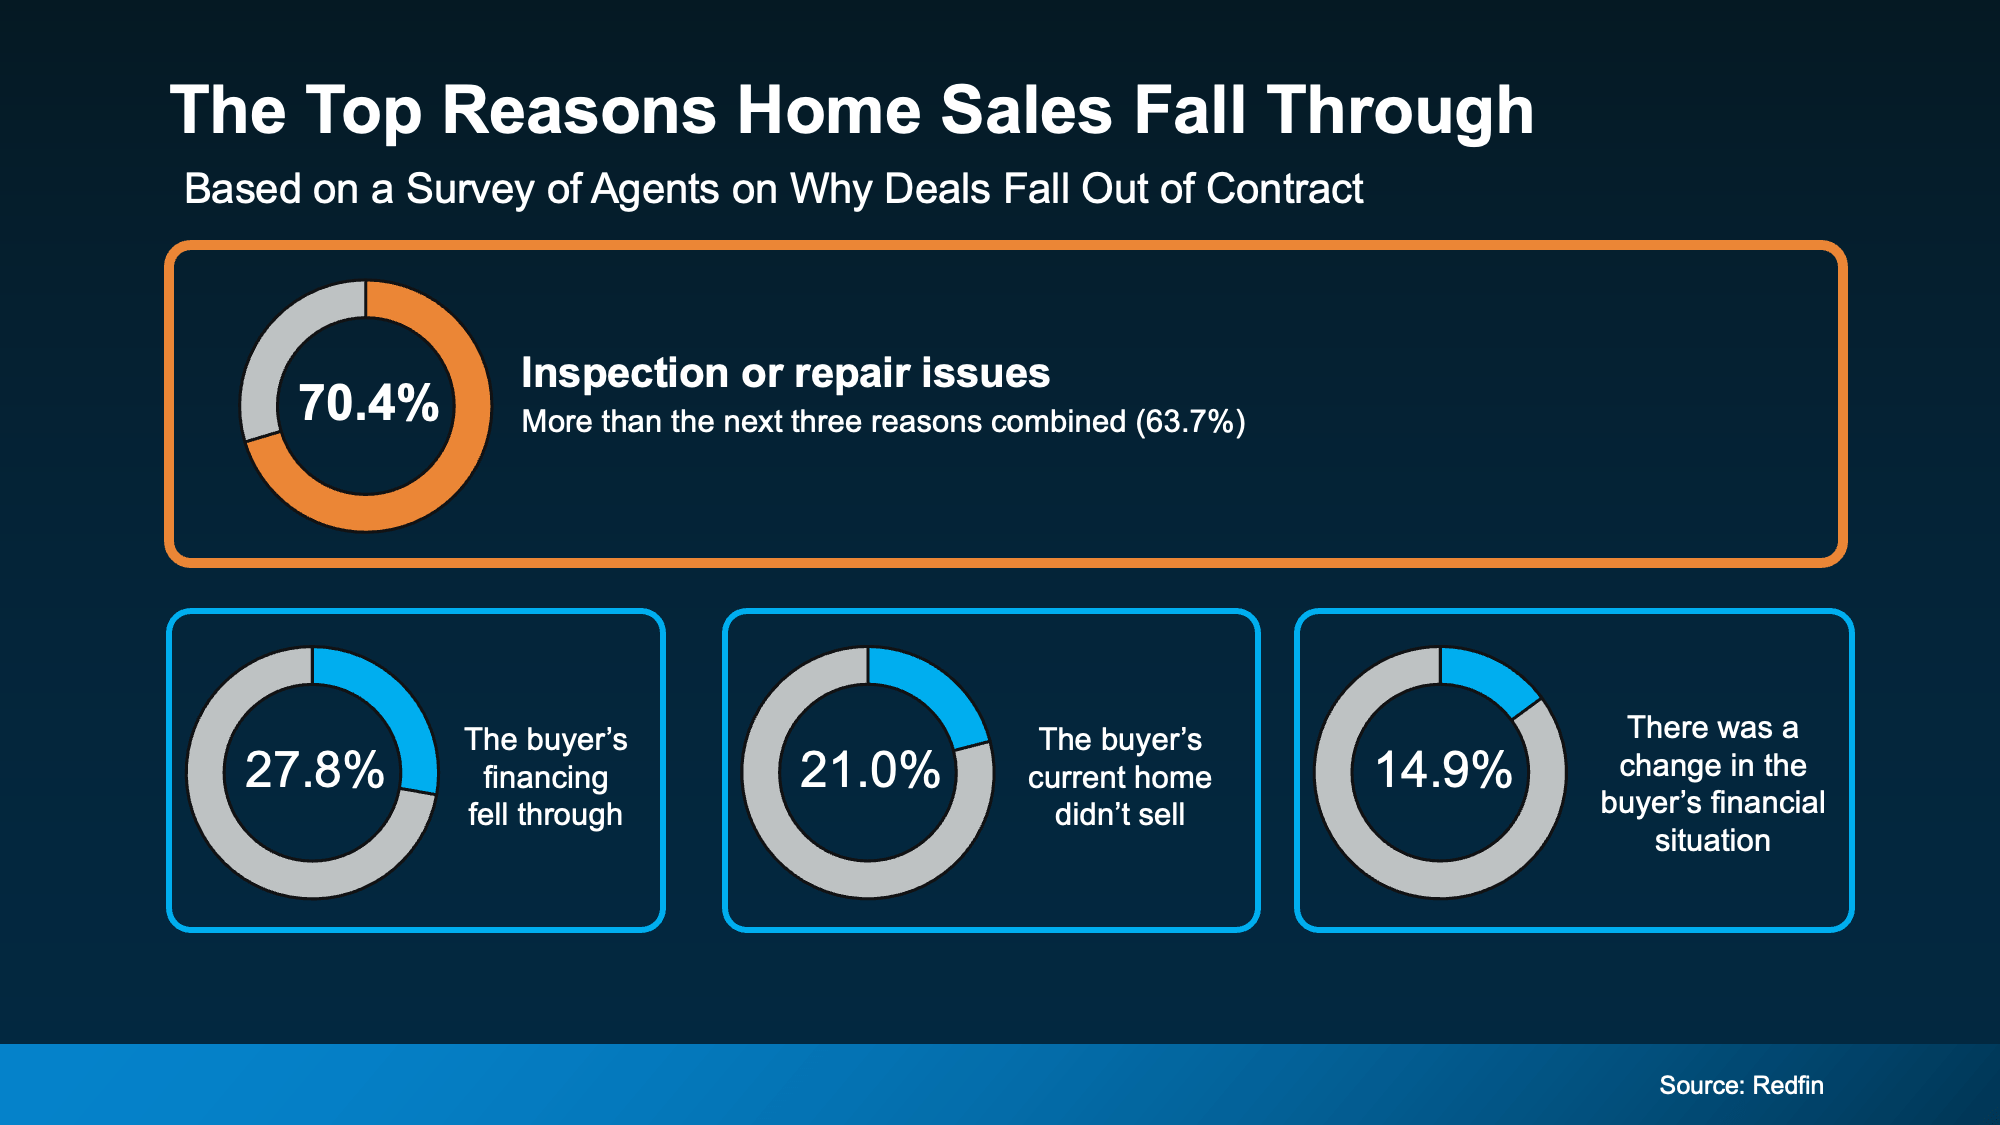
A Redfin survey sheds light on the most common things that trip up a sale (see visual below):

a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.

  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward. 

  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.

  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you're under contract. In this situation, your agent will help you decide what's worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.

  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you. 

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

Bottom Line

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish. So, let’s connect and get your house sold. 

Posted in Helpful Tips
Aug. 20, 2026

One Number Could Change Everything About Your Next Move

One Number Could Change Everything About Your Next Move


When's the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor's house sold for. What yours is actually worth right now.

For a lot of homeowners, it's been years. And if you've been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.

Your House May Be Worth More Than You Think

Home values have climbed significantly over the past 5-10 years. And even though today's market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.

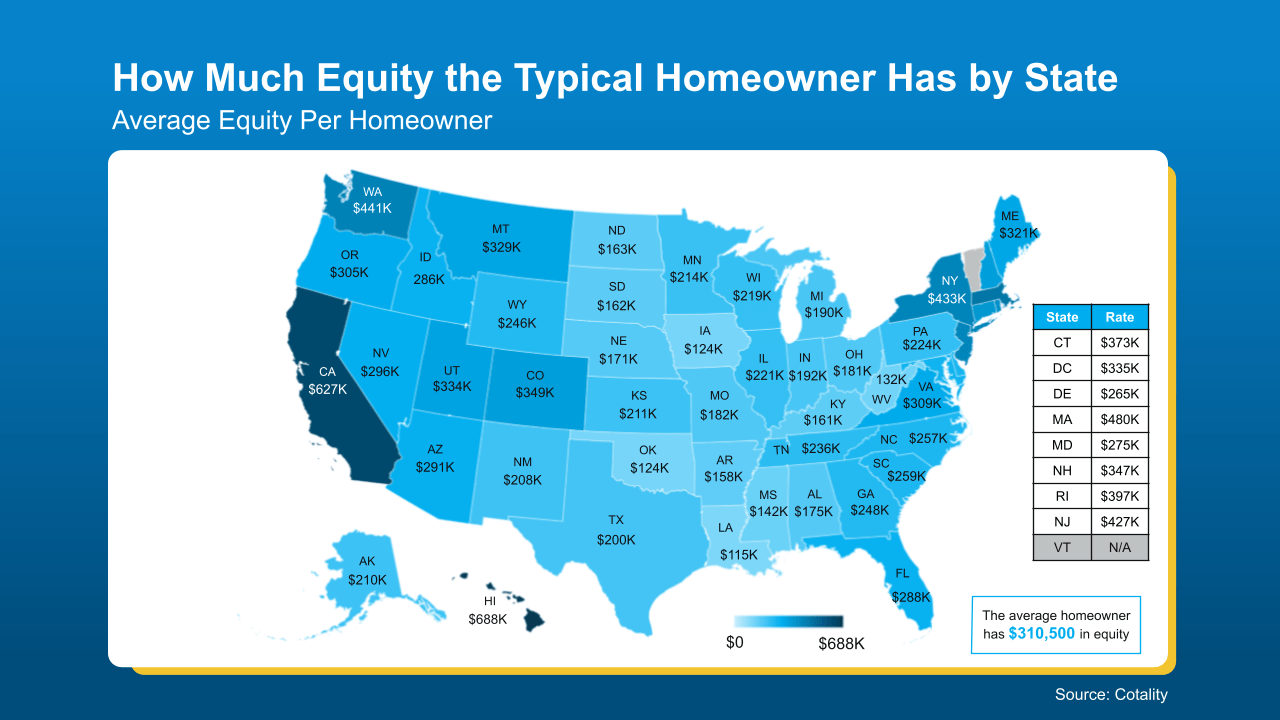
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That's not a small number. It’s six figures.

And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):

a map of the united statesEven though every local market is different, the question you should be asking right now is the same: How much equity have you built up?
Because if you don’t know that number, you’re missing out.

This Could Be the Missing Piece in Your Move

Most people assume that because prices are higher and rates aren't at 3% anymore, moving just isn't realistic right now, especially if they already have an ultra-low rate. And that's understandable – those are real factors.

But they're not the only factors.

When you have that much equity in your house, you're not starting from scratch. You're not scraping together a down payment or hoping the numbers work. You're walking into your next move with more of an advantage than you think. And that changes the math. 

What Your Equity Can Do for You

Maybe you've outgrown your current house or you're ready to downsize… The equity you've built could help bridge the gap between where you are today and where you want to be next.

Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you've built, it could help you:

  • Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today's rates, borrowing less can make a big difference in what you pay every month. 

  • Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July. 

  • Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.

Your equity doesn't erase the challenges of the current market. But it does mean you're walking into your next move with a lot more power and flexibility than you think.

That’s why the value of your home isn't something you should have to wonder about. 

If you're even thinking about a move – or if you're just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.

Because once you see the number, maybe it’s not about whether you can afford to move – it's about what kind of move makes sense for you.

Bottom Line

If it's been a while since you've gotten a professional look at your home's value, let's change that. 

Reach out for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you've likely built, and what that could mean for your next move.


Posted in Helpful Tips
July 20, 2026

More Homes, Better Prices: A Buyer’s Summer

More Homes, Better Prices: A Buyer’s Summer


If you’ve thought about buying a home in the past few years, you may have run into two frustrations: asking prices that kept climbing and too few homes to choose from.

In many places, both sticking points are letting up this summer, with lower asking prices and more homes for sale. Let’s look at the trends, and what they mean for your search.

Sellers Are Pricing To Attract Buyers

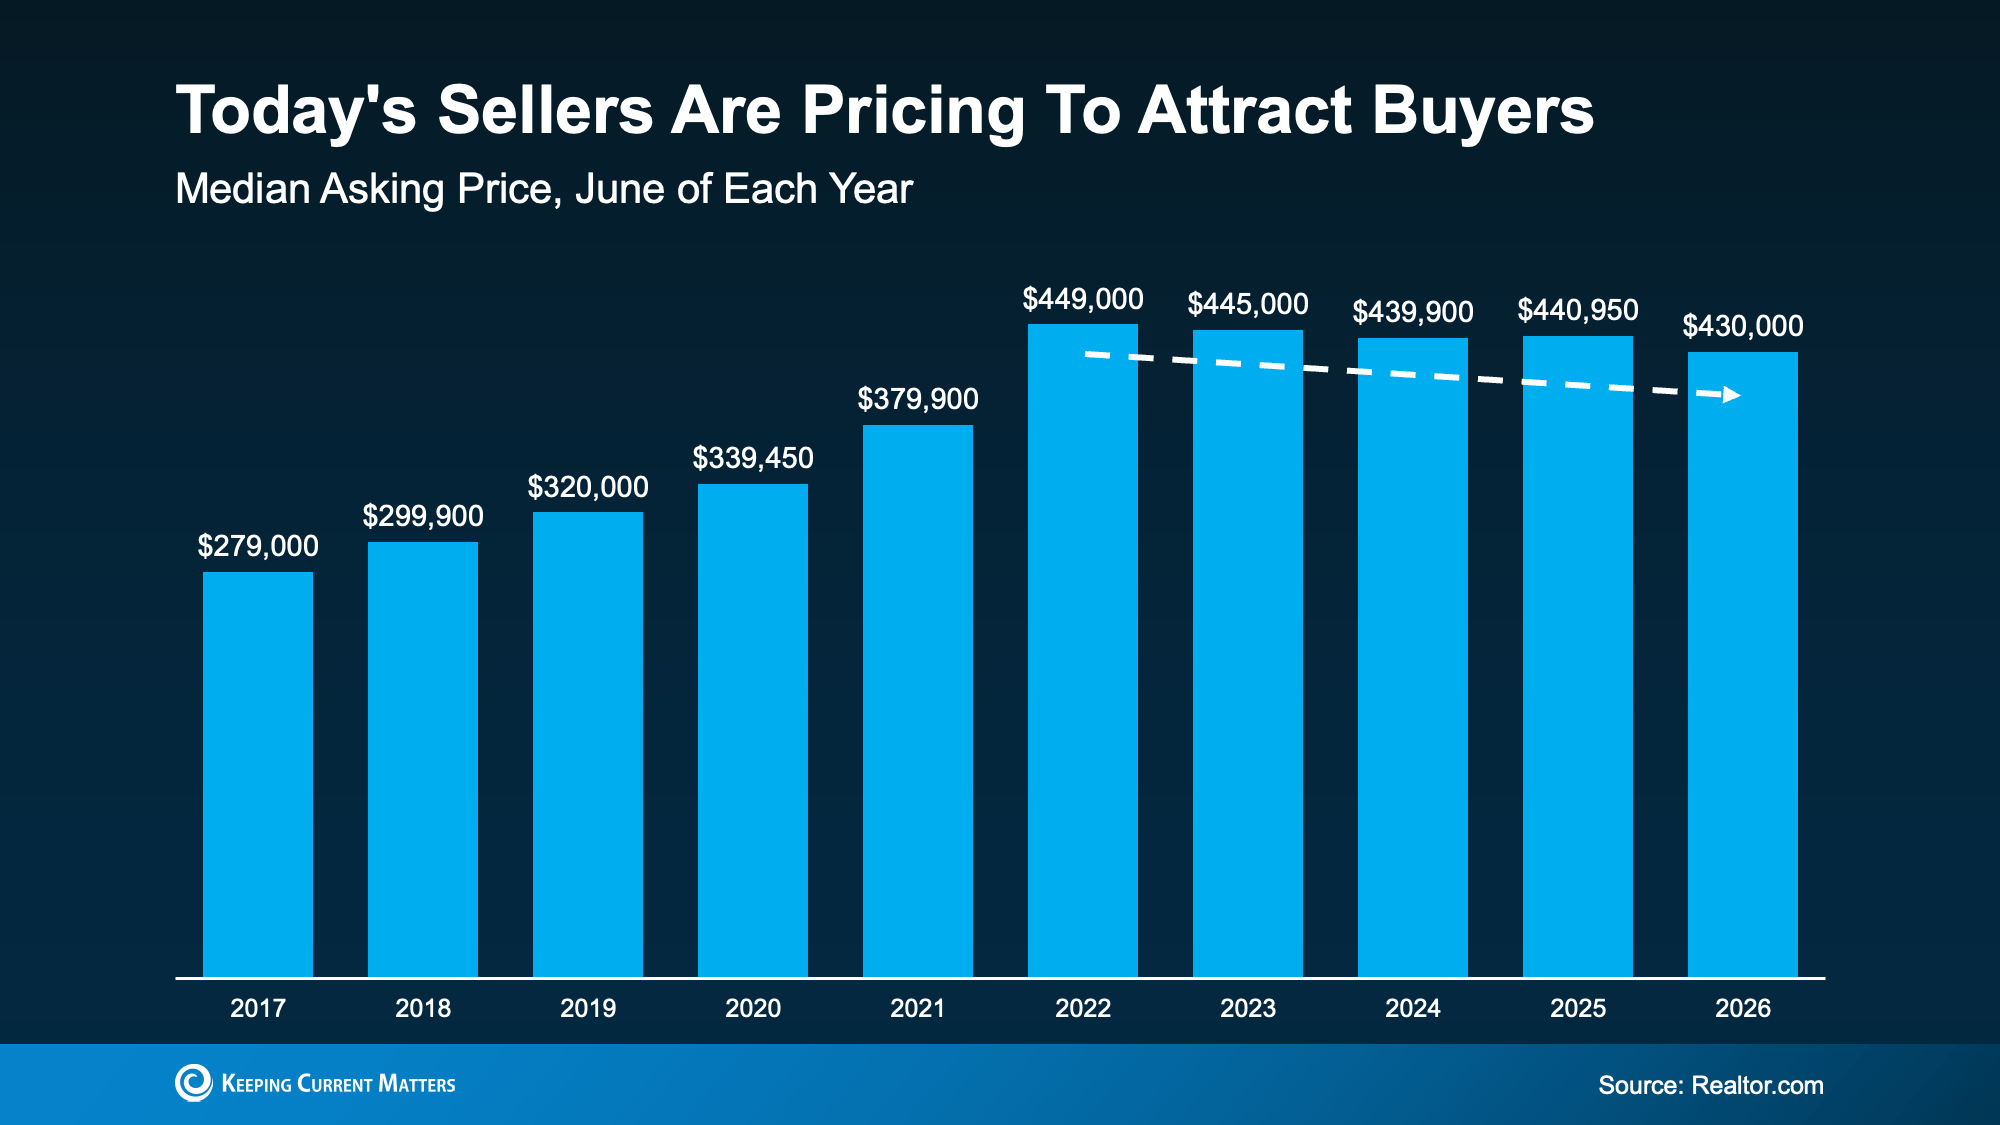
According to Realtor.com, the national median asking price was $430,000 in June, nearly $11,000 under what it was the year before (see graph below):

a graph of sales

That’s the eighth month in a row that the typical asking price has dipped below where they were the previous year, according to the same Realtor.com report.

And while falling prices can sound worrying, this isn’t a sign of an impending crash. We’re talking about asking prices, not sold prices. This is a sign that today’s sellers are meeting the market where it is and pricing to draw buyers. And that’s actually something normal we’d expect from the market. As Danielle Hale, Chief Economist at Realtor.com, puts it:

“Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids. This is a welcome sign that we are in a functioning market.”

Asking prices were never going to climb forever – now they're just settling closer to what buyers can actually pay. That signals a healthier market, and sellers re-adjusting their expectations. 

More Homes Are Available Now

If you’ve spent the past few years watching homes disappear before you could even schedule a tour, this is for you.

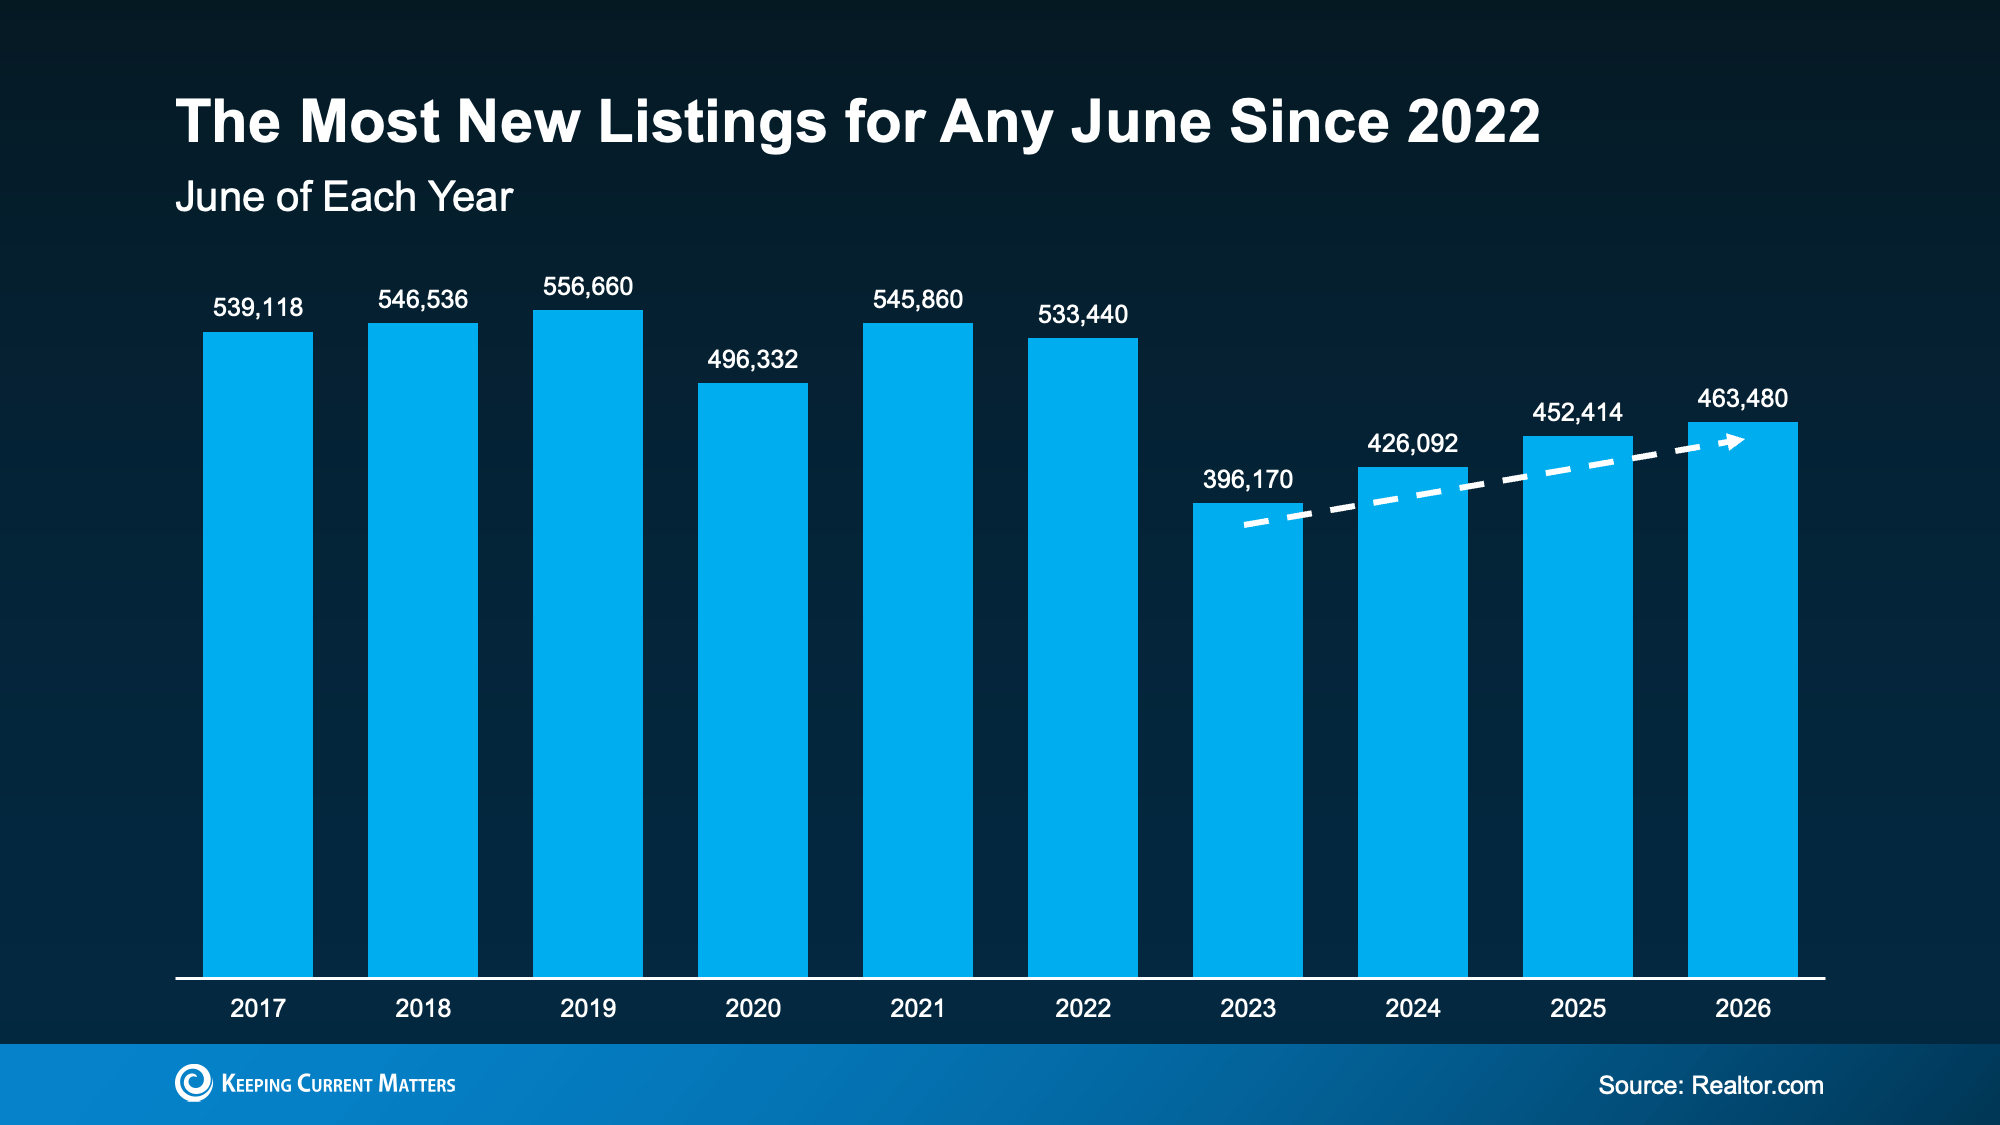
Supply is starting to catch up. According to Realtor.com, the number of homes listed for sale in June was the highest June number we’ve seen in three years (see graph below):

a graph with numbers and a number of blue bars

This means more options for you and less competition for each one.

Now, supply is not back to normal everywhere. As you can see, we’re still down from where we were back in 2017-2019. But in many places, it’s better than it’s been in a while. Here’s how that helps you.

You don’t have to rush an offer just to stay in the running, and you have better odds of finding and landing the right home, not just the one that’s available. Plus, you’ll have more room to negotiate, so you’re searching from a stronger position than buyers had even a year ago.

Why This Is Encouraging if You’re Buying Your First Home

For first-time buyers looking for lower-priced homes, these trends line up especially well. Mischa Fisher, Chief Economist at Zillow, explains:

“The lowest price tiers are exhibiting some softness in terms of price, they also had the most listing-activity growth, the first time since 2022 that’s been the case.”

So, if you’re searching for your first place or your next house, there's a little more to choose from and a little more give on price.

Bottom Line

If a tight budget or a thin selection has kept you from buying a home, now might be the time to restart your search.

Ready to see what’s available here? Let’s connect.

Posted in Buying
July 13, 2026

What To Expect from the Housing Market in the Second Half of 2026

What To Expect from the Housing Market in the Second Half of 2026


If the first half of this year has left you feeling stuck, you're not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That's why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here's what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven't come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It's too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone's patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

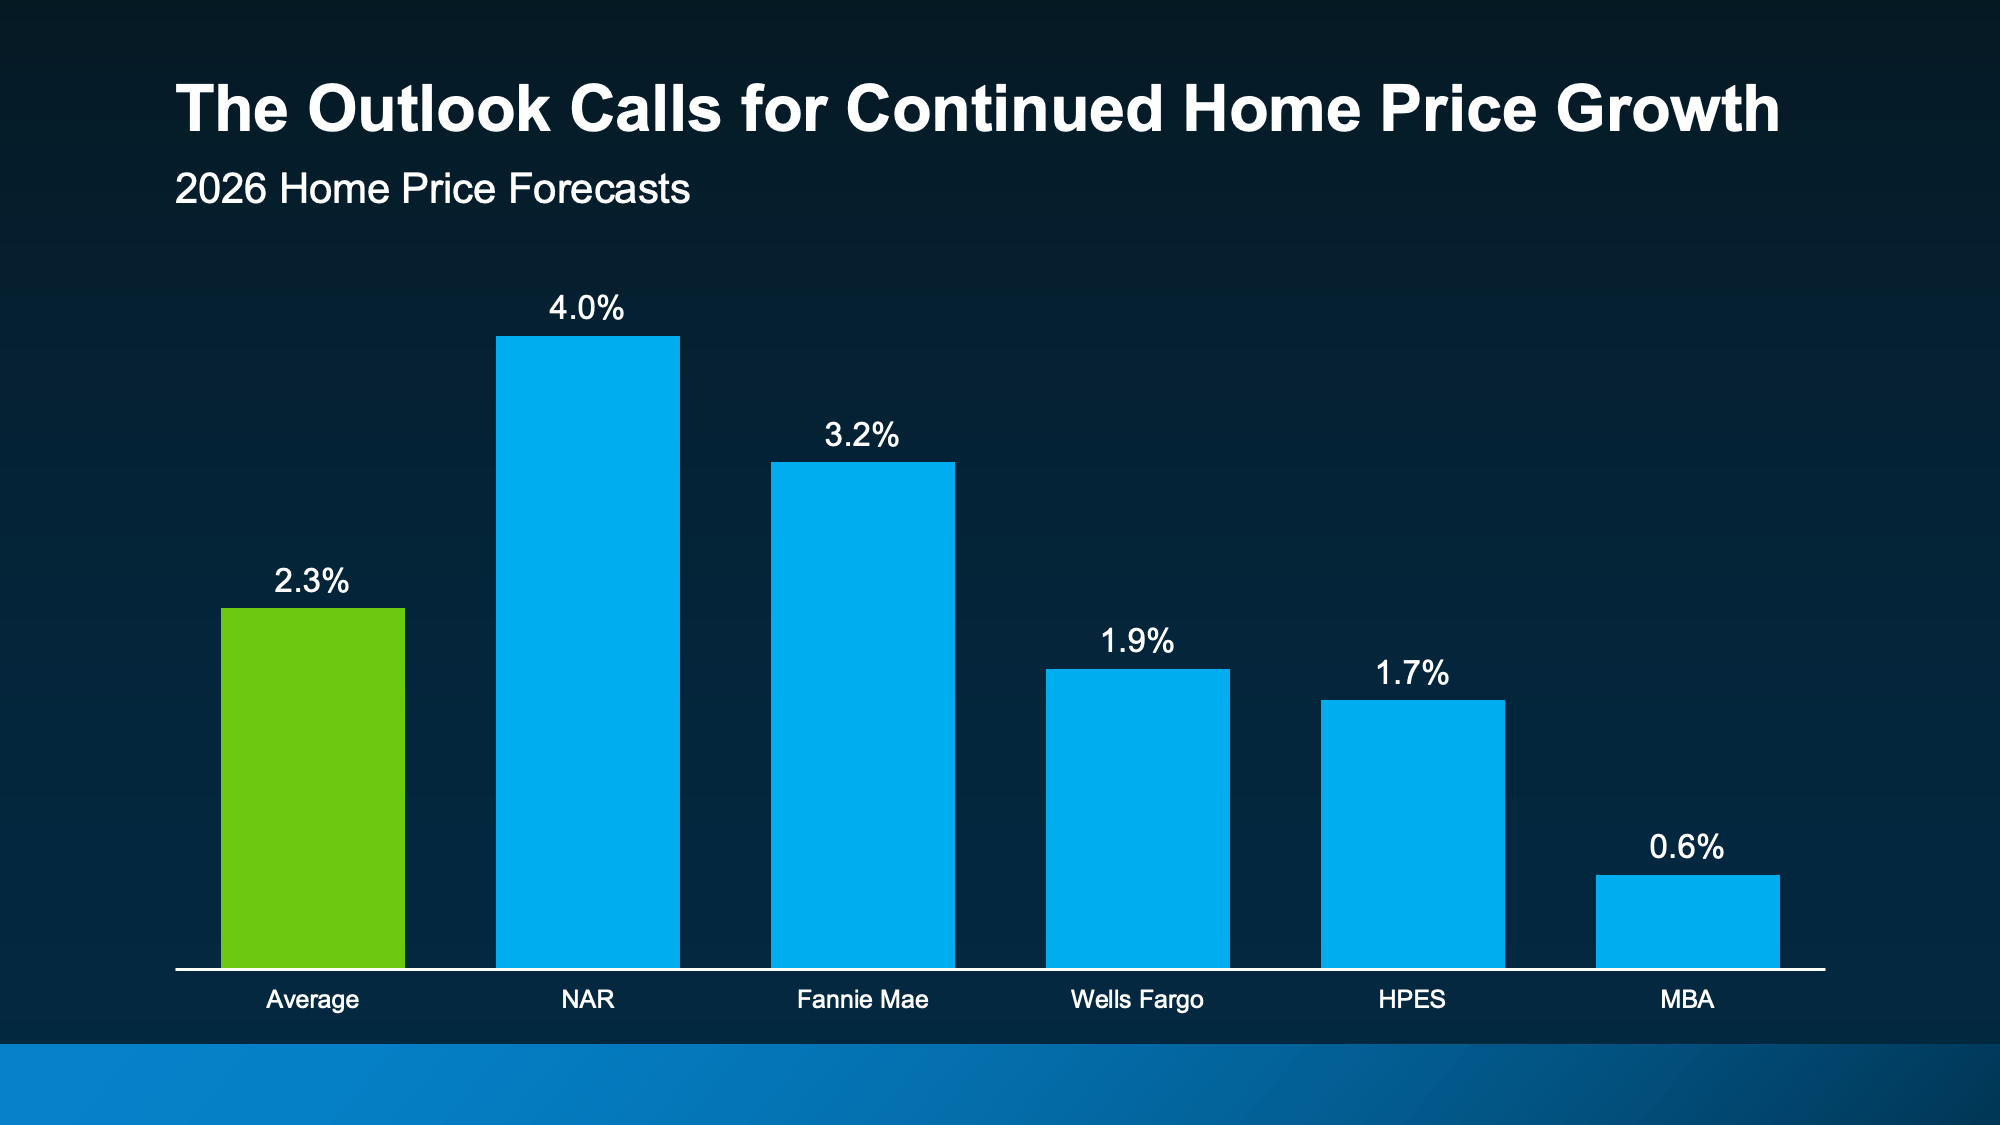
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you've been wondering why the housing market has felt quieter lately, you're not imagining it. Home sales have been slower than many experts expected. But that doesn't mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon. 

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.” 

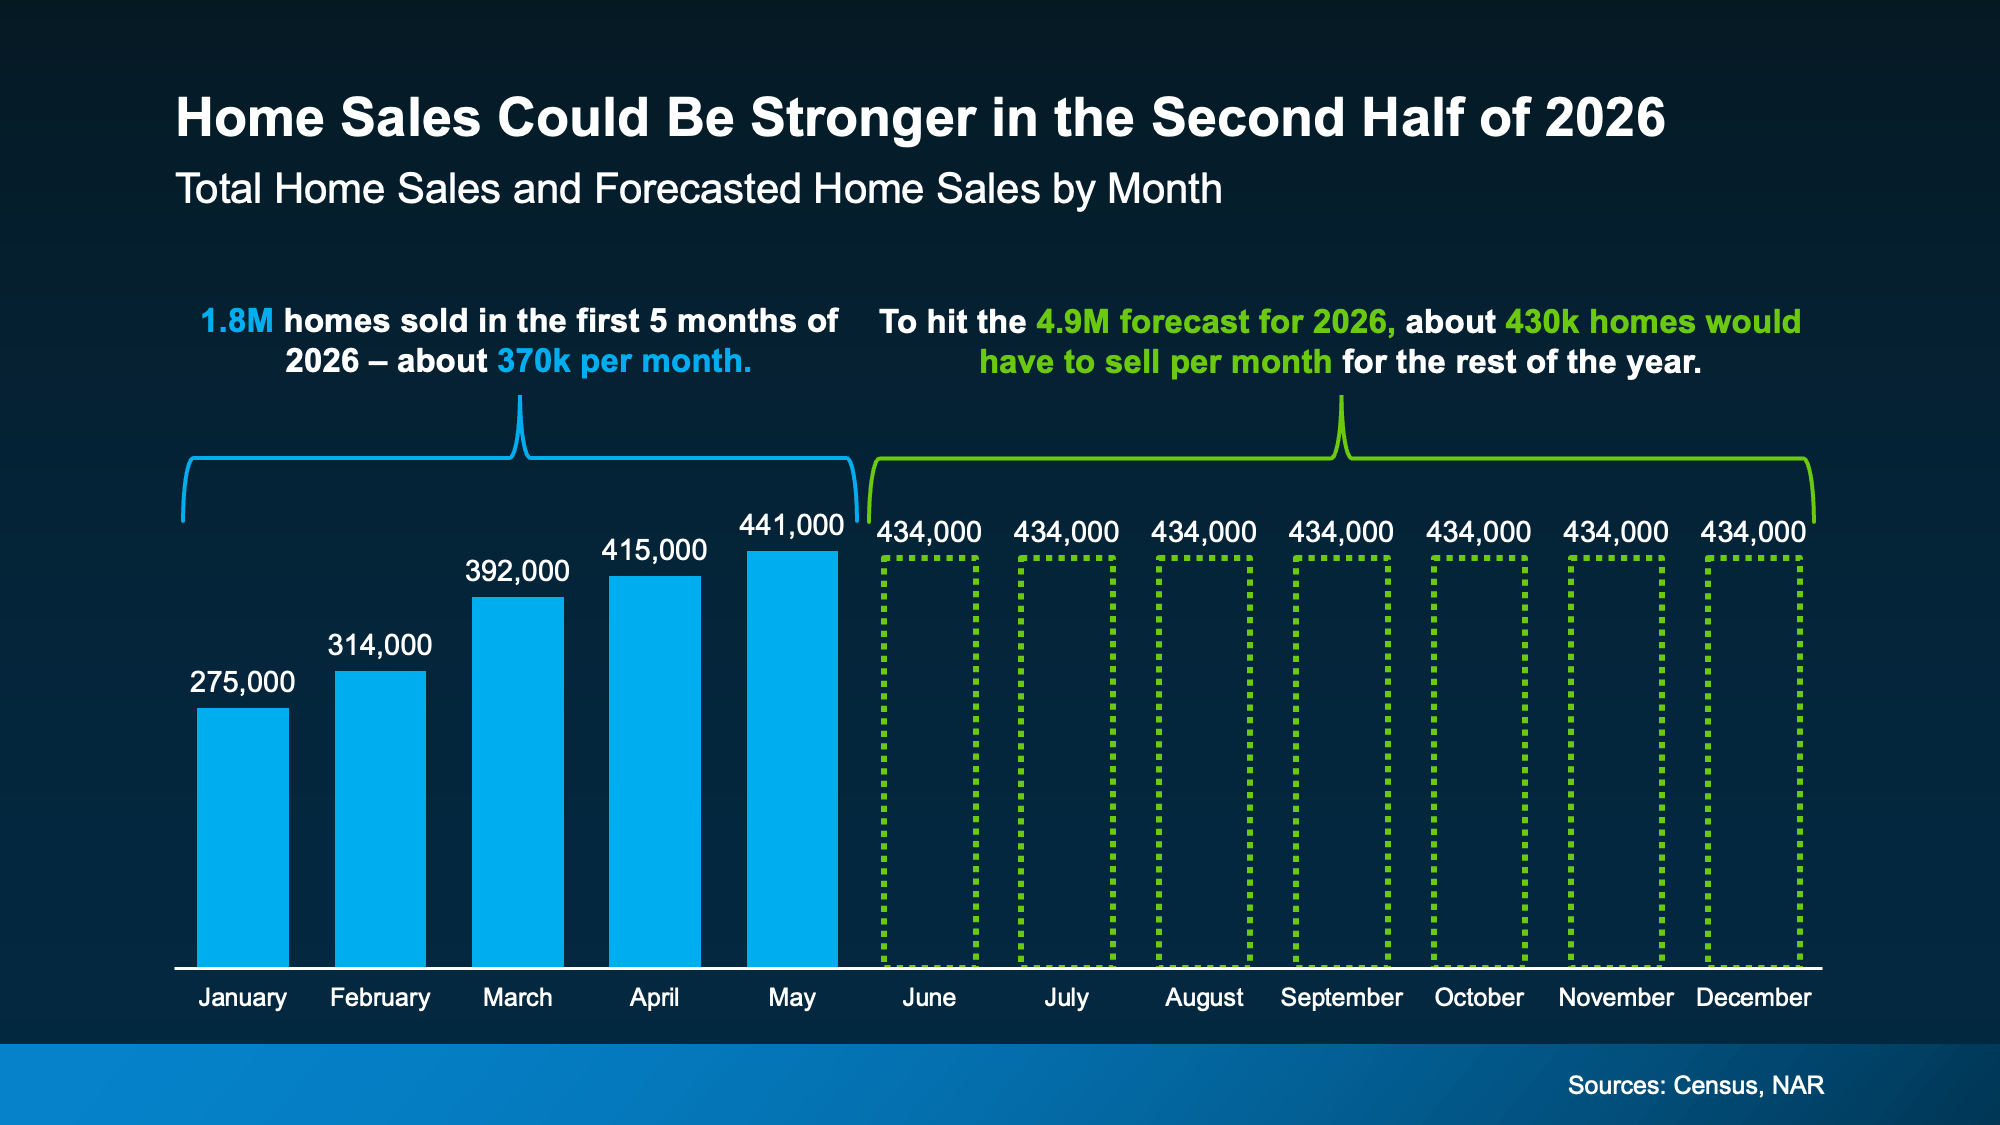
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we've had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you've got the chance to be one of them.

Bottom Line

The second half of the year probably won't be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you've been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in our local market, let’s connect.

Posted in Market Updates
June 29, 2026

Your House Didn’t Sell. Here’s How To Turn It Around.

Your House Didn’t Sell. Here’s How To Turn It Around.


When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence. You start second-guessing everything, including the decision to move in the first place. And that raises 2 big questions: 

Do you try again?

Is that even worth it?

Here’s the secret to getting a better outcome the second time around.

Different Agent. Different Results.

Most sellers who re-list and ultimately sell don’t wait for market to magically change. They change their approach. And there’s data to back that up.

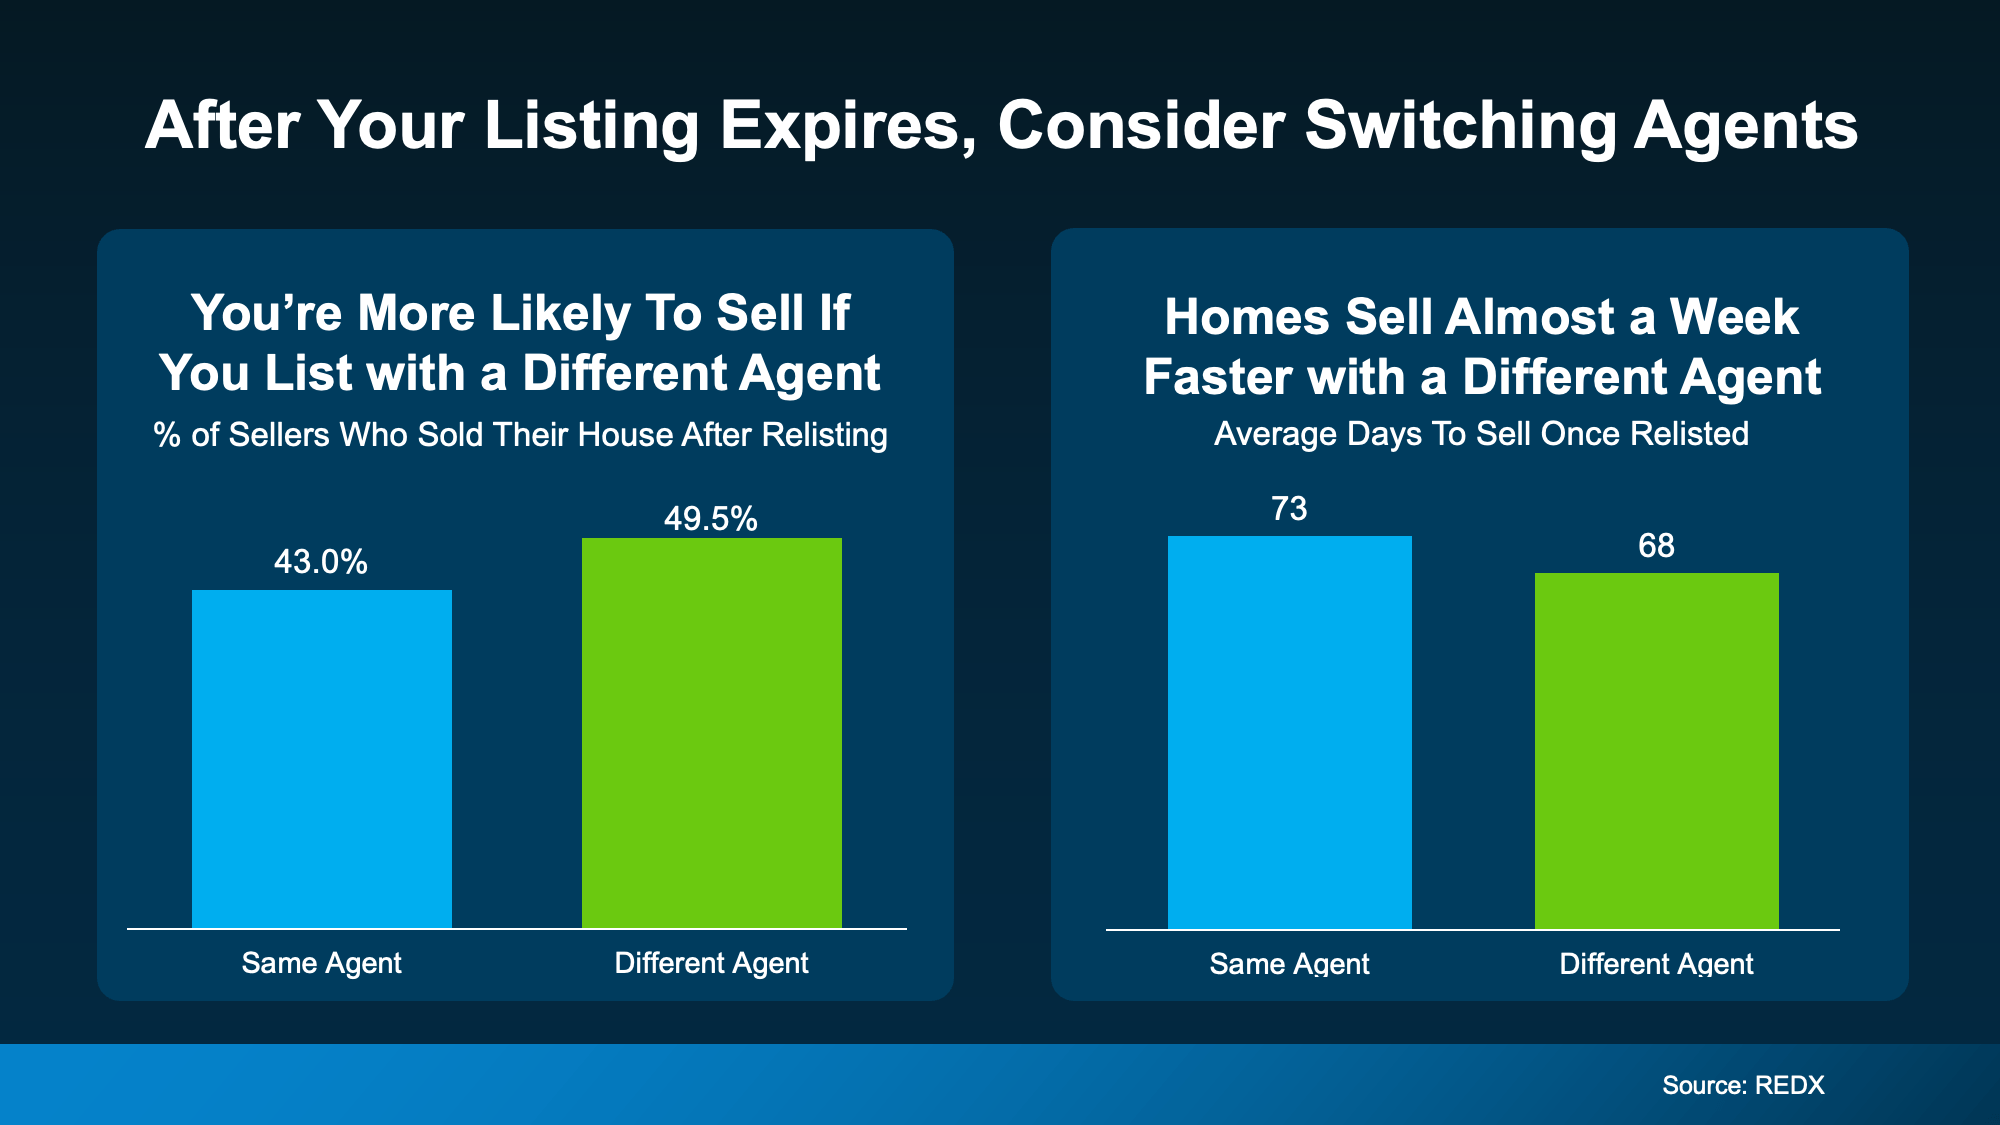
Research from REDX shows homeowners who put their house back on the market with a different agent are more likely to sell than homeowners who re-used the same agent. Not to mention, they see their homes sell faster (see graph below): 

a screenshot of a graph

That’s the power of a fresh set of eyes. Because in a moment like this, the worst thing you can do is rerun the same set of plays and expect a different outcome. A different agent can bring a new perspective on where things went off track – and a lot of the time, one of these things happened.

1. The Asking Price Didn’t Match Buyer Reality

There’s a saying that’s especially important in today’s market, and it’s: “if your price isn’t compelling, it’s not selling.” Maybe that’s what happened with your house.

With mortgage rates where they are and inflation driving up the cost of everyday purchases, buyers have less room to stretch. If they feel like your house is priced even a little high, it’s going to get skipped over. And if no one looks at it, it's not going to sell.

The Fix: Price to draw buyers in, not push them away. Have an agent pull fresh data from recent sales so your asking price matches what buyers are actually paying right now. 

2. The First Impression Didn’t Win the Click 

Most buyers decide whether they want to tour a home in seconds. If the photos look dark, or dated, they scroll right past. And while you may think: “If they just saw it in person, they’d get it,” you may not get that chance.

And honestly, even in person, small things can quietly kill momentum – worn down paint, outdated fixtures, clutter, or a yard that feels high-maintenance. Individually, they’re small. Stacked together, they create doubt.

The Fix: Walk the house like you’re a buyer, not the owner. Start with what’s easy and obvious – paint, lighting, curb appeal, decluttering. Then update the photos so they match the best version of your house.

3. The Marketing Was Too “Set It and Forget It”

Today, the number of homes for sale has grown in many areas. Buyers have more options, which means your house needs a plan to stand out. A generic description and a basic upload to the MLS can blend in fast.

The Fix: Find an agent who can build stronger exposure through digital marketing and social platforms, plus content that makes buyers stop – strong photos, a smart description, a video walk-through, and a plan for open houses and follow-up.

4. There Was No Clear Plan for Feedback

Sometimes the house gets showings, but no offers. If that was your experience, it actually tells you something important. Buyers liked it enough online to come see it. So, something else was holding them back.

Those buyers were sending a message. It just wasn’t translated into action. 

The Fix: Make sure your agent has a clear plan for seeking out and acting on feedback quickly. That dialogue often points to the one change that would get a house sold.

5. The Deal Couldn’t Get Over the Finish Line 

Even when a house is priced well and marketed right, deals fall apart when there’s no plan for the human side of the transaction.

Buyers today are more likely to ask for repairs, credits, or help with closing costs than a few years ago. In this type of market, being unwilling to negotiate can cost you more than a reasonable concession ever would.

The Fix: Decide ahead of time what matters most to you and where you can be flexible. Keep the dialogue open and lean on your agent for advice.

Bottom Line

If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner.

When you're ready for a fresh set of eyes on what happened and what to change first, let’s connect.

Posted in Helpful Tips
June 22, 2026

That House That’s Been Sitting Could Be Your Best Shot at a Deal

That House That’s Been Sitting Could Be Your Best Shot at a Deal


Open up a home search and you'll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

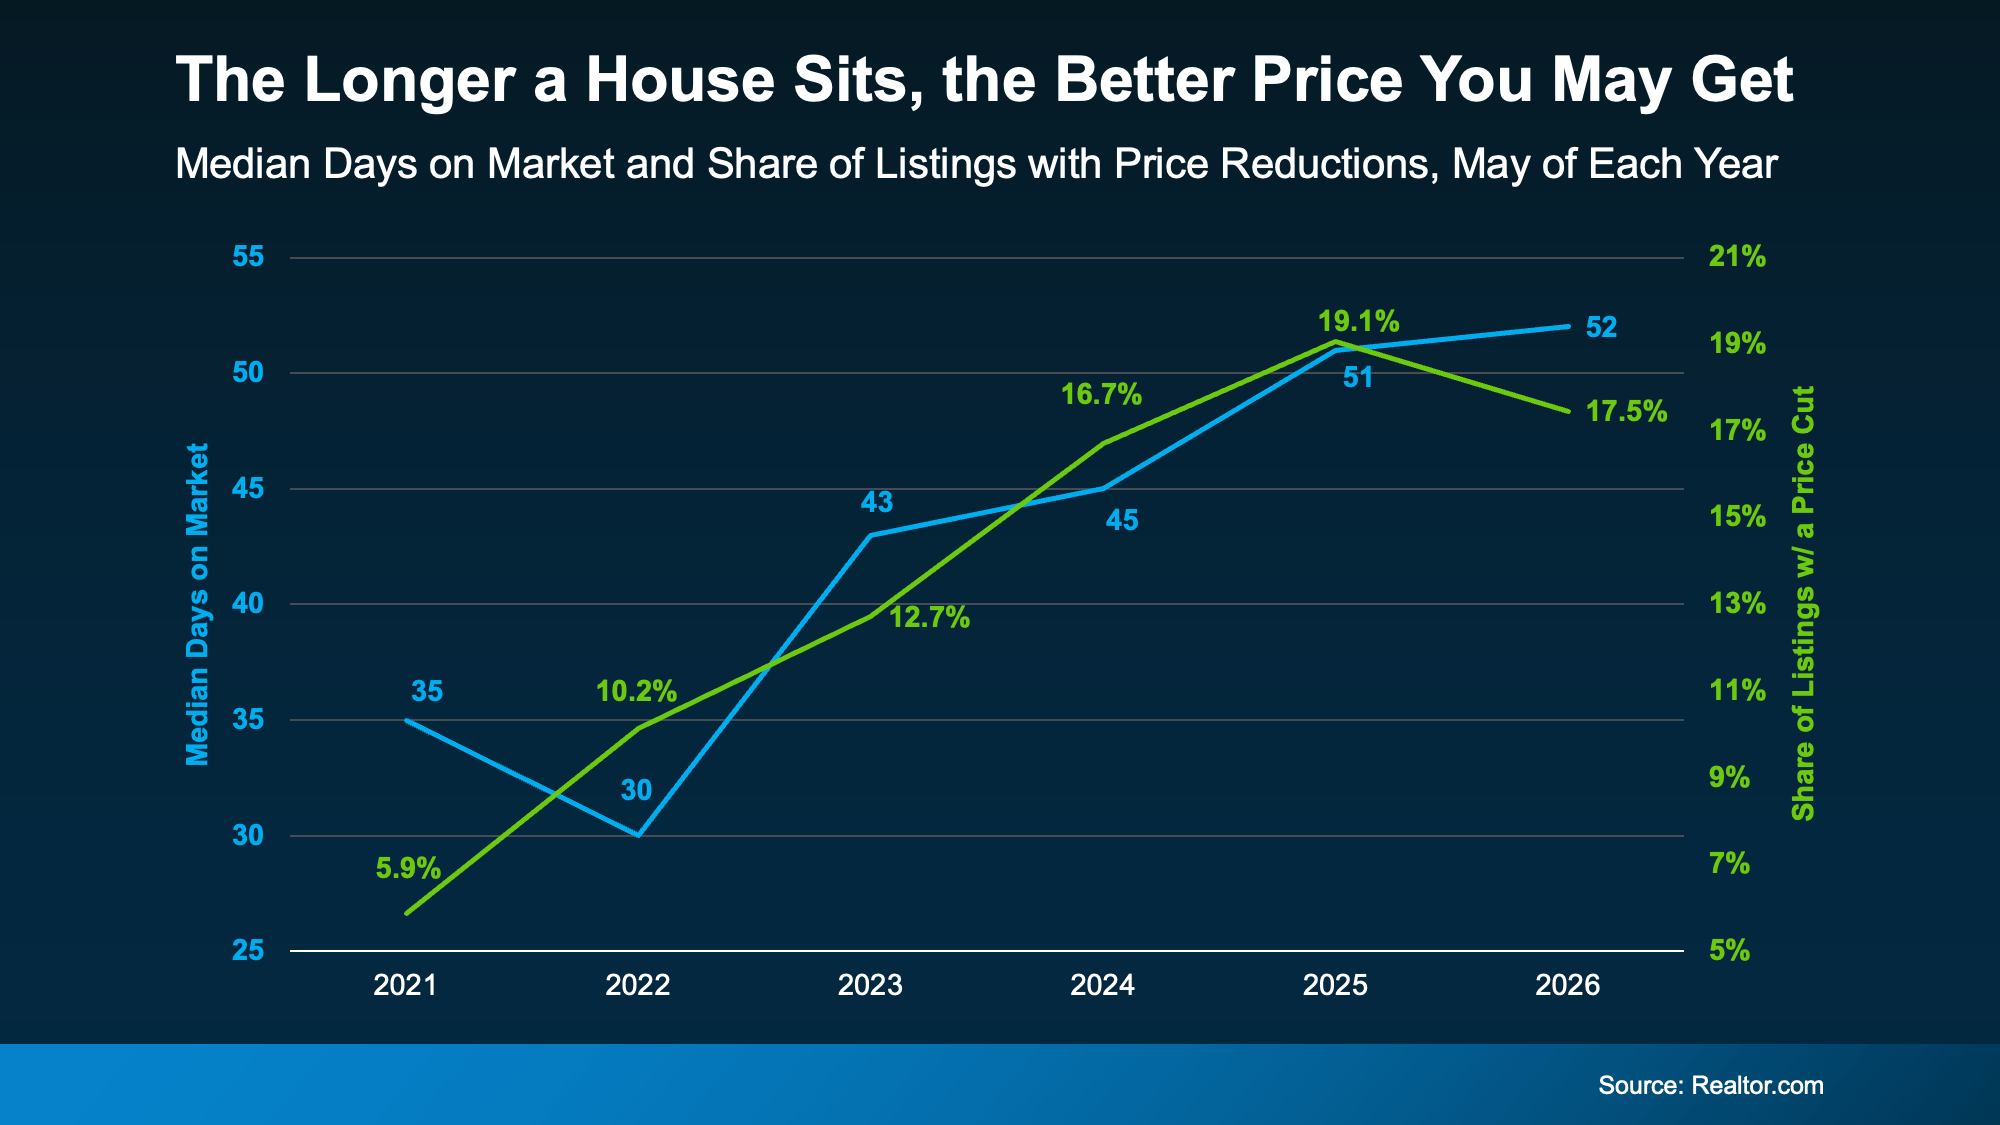
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

Bottom Line

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, let’s connect.

Posted in Helpful Tips